THE ERRATA
The Errata No.9
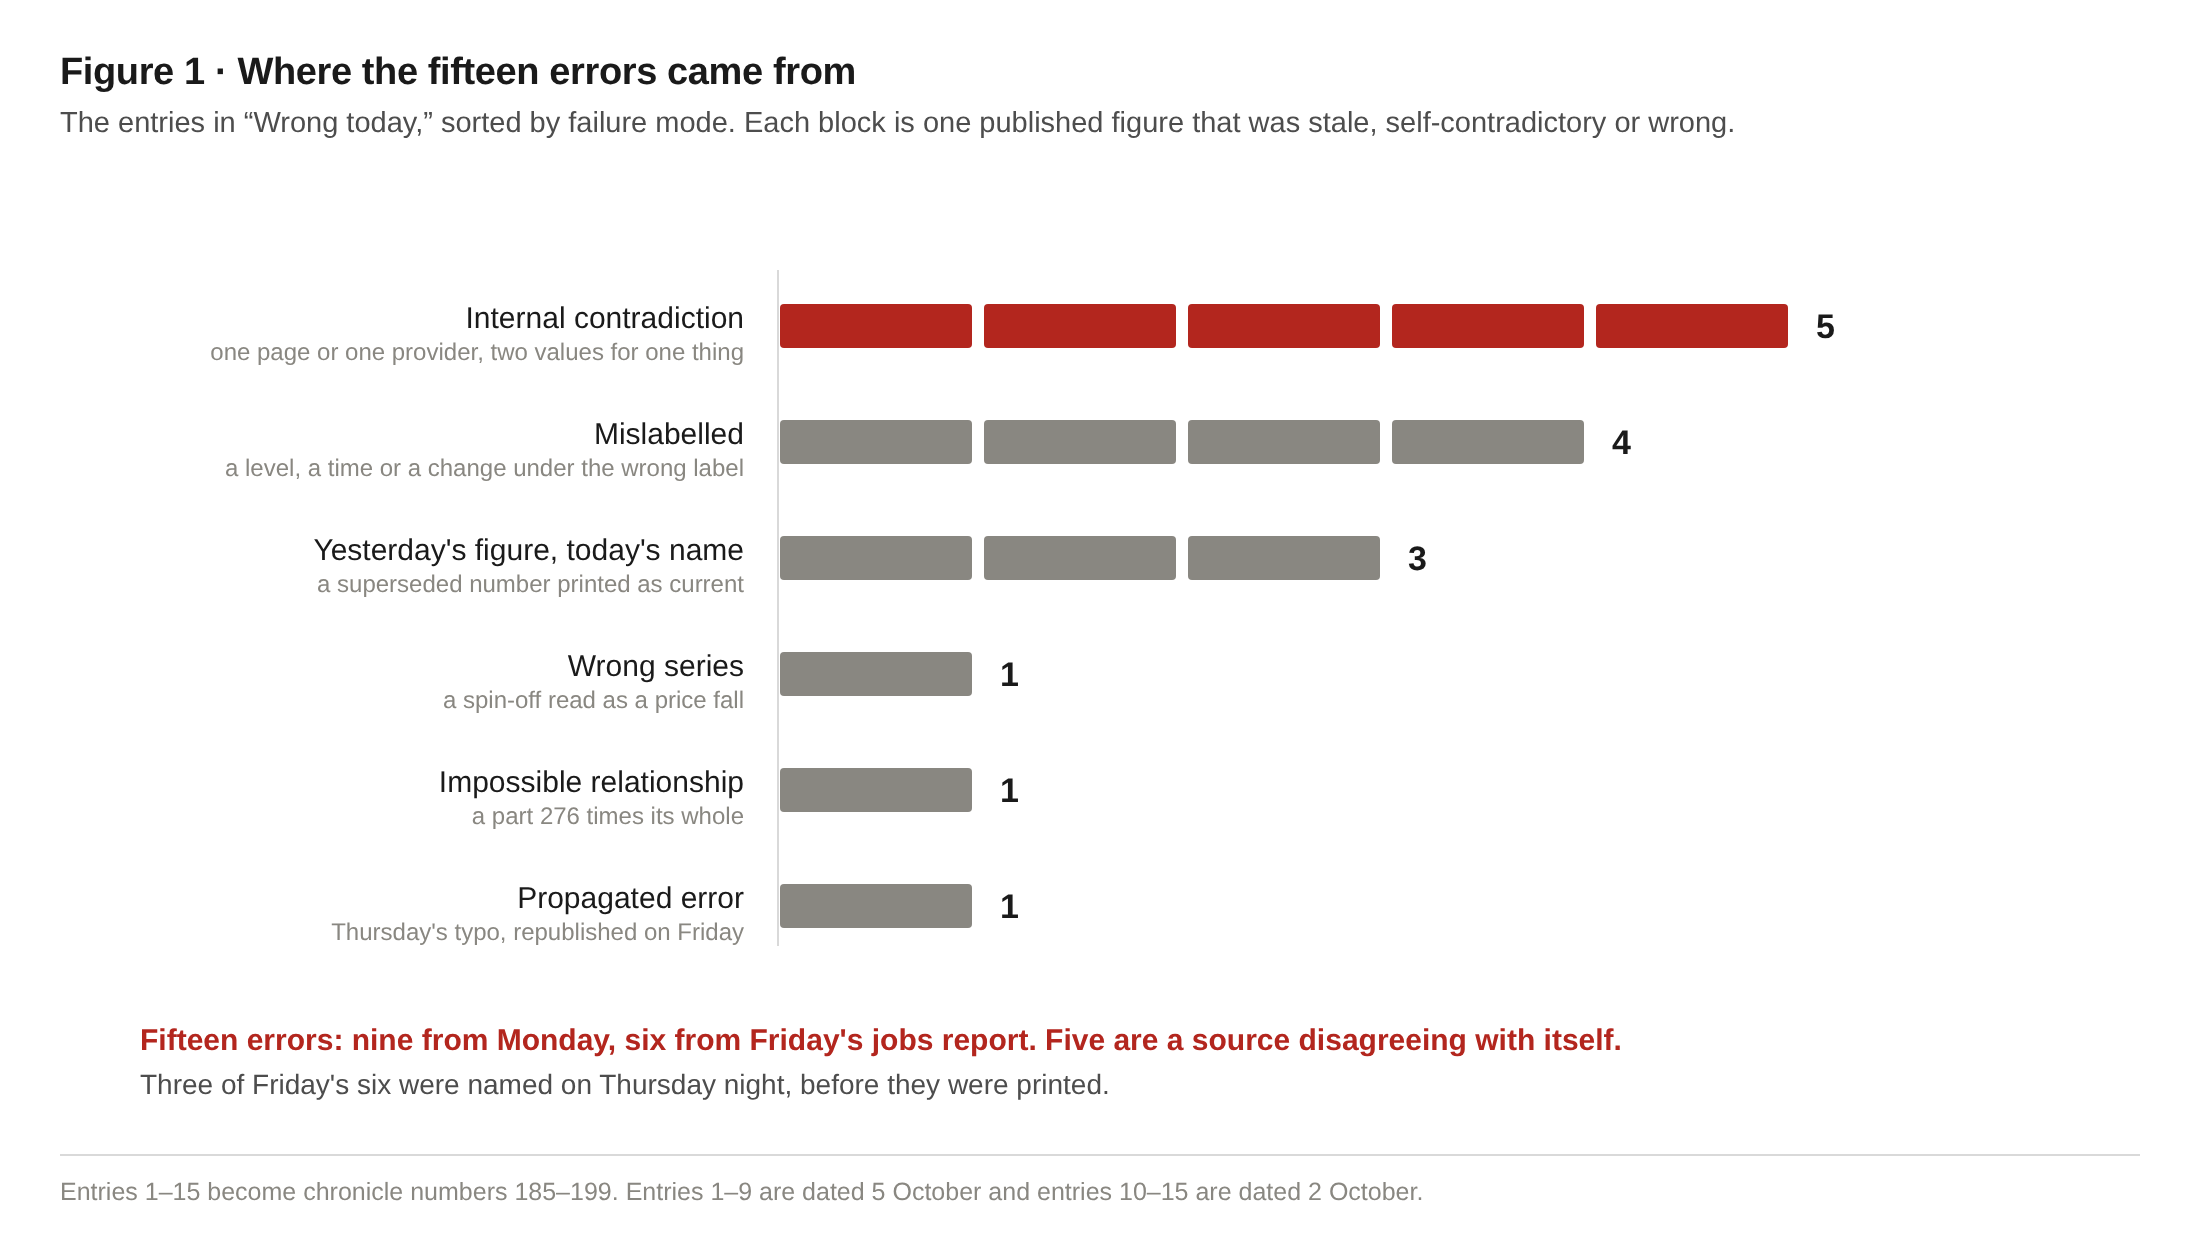
Fifteen errors: nine from a session that ended with the Nasdaq at a record, six from Friday's jobs report. Thursday's forecast is scored, the ten-year is reconciled value by value, and eight errors are named for Tuesday before they are printed.
The Nasdaq closed at a record on Monday and the ten-year Treasury yield, on the wires' count, closed at its highest in twenty-four years. Most outlets printed both facts correctly and a few printed them wrongly, and the few are the subject here.
Fifteen entries tonight: nine from Monday and six from Friday's jobs report, which this sheet forecast on Thursday and scores now. Then the ten-year, value by value, and eight things to expect from Tuesday.
Wrong today
1. A services index that rose in the morning and fell by the afternoon. Yahoo Finance's live blog, in its 10:15 a.m. version: "The ISM Services PMI came in at 55.9 in September, up from 55.4 in August and above the consensus forecast of 55.7," under a title "accelerated." The Institute for Supply Management's release says the index "registered 54.9 percent, a decrease of 0.5 percentage point." By 4:01 p.m. the sentence read "54.9 in September, down from 55.4 in August and above the consensus forecast of 55.7." "Above" stayed, over a figure that is below. AOL's copy still says 55.9. Caught against the primary document.
2. Friday's close, a day old. The same blog at 9:41 a.m. had the ten-year yield hovering "around 5.3% early Monday after finishing Friday near 5.24%." The Treasury's table has Friday at 5.28. Thursday was 5.24. The page's own lead says the yield "rose 3 basis points to 5.31%," which also puts Friday at 5.28. Its morning lead called the level "near its highest levels since 2007," a mark the yield passed last week. Caught against the Treasury's table and the page's own subtraction.
3. A record twenty years out. Trading Economics: "The US 10-year Treasury yield climbed to 5.33% on Monday, near its highest level since March 2022." A news item on the same page: "5.35%, the highest since April 2002." Benzinga carried the first version at 12:53 p.m.: "near its highest since March 2022." Reuters reported on Thursday that the yield had passed its 2007 peak, so no level from 2022 is anywhere near it. Two outlets, one error, counted once. Caught by reading down the page.
4. A close that was not the close. 24/7 Wall St.'s closing card: "S&P 500 closes at 7,787 as Nasdaq leads broad market higher," with the index "at 7,787.91," up 0.84 percent, and the Dow up 0.36. The S&P 500 closed at 7,773.95, up 51.23 points, or 0.66 percent, and the Dow rose 0.18 percent (the Associated Press; TheStreet). 7,787.91 is a level from late in the session, inside the day's range of 7,727.59 to 7,794.35. Thursday's card did the same (entry 179). Caught against the sworn close.
5. Friday's two-year under Monday's stamp. The same outlet's 7:00 p.m. card: "the 2-year up another 5 basis points to 4.83%." Up five to 4.83 is Friday, to the basis point: the Treasury has 4.78 for Thursday and 4.83 for Friday. On Monday the two-year stood at 4.823, down 0.2 basis points, on TheStreet and at 4.821, down 0.4, on Kiplinger. Friday's card did this with Thursday's rows (entry 183). Caught against the primary table.
6. One page, two Brents. Investrade's closing review states: "U.S. WTI crude oil futures settle at $89.43 per barrel, down -$1.68, or 1.84% while Brent Crude futures settle at $100.32 per barrel, down -$1.93, or 1.89%." In its table: WTI 89.43, down 1.68, beside Brent 101.17, down 1.08. The Brent row is the one from the mid-morning table, left in place. Both versions count from the same Friday settlement of $102.25. Caught by the house rule that oil never travels alone.
7. A ten-year at 4.30 percent. Investrade's mid-morning table: "10-Year Note | 0.021 | 4.30%." Its morning table was 5.287, and its closing table was 5.347. A rise of 0.021 from Friday's 5.277 is 5.298. Calculated by adding.
8. Monday's change beside Tuesday's level. Trading Economics' United States index table had the S&P 500 at 7,781.04, up 51.23, or 0.66 percent, dated 6 October, and the Dow at 51,324.29, up 90.94. The changes are Monday's cash session to the cent. The levels are contracts trading after the bell: 7,781.04 less 51.23 is 7,729.81, and Friday closed at 7,722.72. The sentence above the table says the index gained 0.09 percent. This is the fifteenth entry for this page. Caught by subtracting.
9. Tuesday's calendar, an hour early. Investing.com's list of Tuesday's events, published at 2:00 p.m.: "7:30 AM ET - Trade Balance" and "9:45 AM ET - FOMC Member Bowman Speaks." The Census Bureau and the Bureau of Economic Analysis publish at 8:30. The Federal Reserve Board's calendar has Vice Chair Bowman at 10:45. The same outlet put Friday's jobs report at 7:30 (entry 175). Caught against the agencies' schedules.
The next six are Friday's, logged tonight under Friday's date.
10. August, measured from a number that no longer existed. This was forecast on Thursday (No. 8, item 3). ABC News at 8:34 a.m.: "Employers added 29,000 jobs in September, a sharp slowdown from the 162,000 jobs added in August." The release that gave 29,000 also cut August "from +162,000 to +133,000." Investopedia's wrap: "well below the 162,000 figure in August." Two outlets, one error, counted once. Caught against the release they were reporting.
11. A revision printed as a starting point. Kiplinger's jobs piece: "job growth for July (-31,000 to -10,000) and August (-29,000 to +133,000) was revised down." Minus 31,000 and minus 29,000 are the sizes of the revisions. The Bureau of Labor Statistics has July "from +21,000 to -10,000" and August "from +162,000 to +133,000." Caught against the release.
12. A ten-year at 5.52. Trading Economics on Friday: "The yield on the US 10-year Treasury note resumed its rise to 5.52% on Friday after falling as much as 8bps earlier in the session." The Treasury's Friday close was 5.28, four basis points above Thursday's, and the week's high was about 5.34. Caught against the primary table.
13. Eight million jobs in one industry. Breitbart: "Goods-producing jobs added 18,000. Eight million jobs were added in durable goods manufacturing and 11 in construction." The whole economy added 29,000. A part cannot be 276 times its whole. Caught by reading the sentence before it.
14. A spin-off printed as a collapse. This was forecast on Thursday (No. 8, item 8). My Weekly Stock's recap of the week lists "$CTVA (Corteva): -84.8%" as the worst performer in the S&P 500 and never mentions the Vylor spin-off, which accounts for the fall. HDFC Sky's headline has Corteva "Plunges 84.31%"; its body does mention the spin-off. Caught by searching the page for the word.
15. The 910K, traveling. This was forecast on Thursday (No. 8, item 1). investingLive's "Consensus estimate +910K (range +35K to +180K)," entry 173, was republished under Friday's date by SwingFish and still stands on finwire. investingLive's own Friday story used 90,000. Caught against the range beside it.
The forecast, scored
Thursday's sheet named nine errors to expect in Friday's coverage of the jobs report. No sheet ran on Friday, so they are scored here.
Five occurred as named. The 910K surfaced elsewhere (item 1, entry 15). August was measured from 162,000 after the revision (item 3, entry 10). Thursday's index changes sat beside Friday's contract levels on Trading Economics' page, read by the Friday Brief between 8:28 and 10:12 a.m. (item 6); that is the pairing of entry 171 and is not counted again. Corteva appeared among the week's losers without Vylor (item 8, entry 14), while the Accenture half of that item turned up only as CV Research's "jumped about 19% to $217.63 on Thursday," against a close of $212.30, up 15.78 percent. And the odds of an October increase were printed in a dozen sizes (item 9): Benzinga had 23 percent before the release and 13 after, investingLive 28 and 15, Yahoo Finance 20 "down from 24% the day before." None said when it looked. Those are differences, not errors, and are not logged.
One occurred in a neighboring form. Item 5 expected the monthly wage figure printed as the annual one. Fox Business printed the reverse: "Average hourly earnings increased 3% in September." They rose 0.1 percent in September and 3.0 percent over twelve months.
Three did not occur. No calendar copied Investing.com's 7:30 (item 2), though the outlet repeated the shift for Tuesday. No outlet printed private payrolls as the total (item 4); the Dallas Express and Wolf Street led with the private 46,000 and labeled it correctly. No Friday-morning recap said yields rose on Thursday (item 7).
One half of item 1 could not occur: 29,000 was below every consensus in circulation, so nobody could call it a beat.
The one number, reconciled
The ten-year again. Here is every value published for it on Monday, in the order of the clocks on the pages; two pages carry no time and sit at the foot.
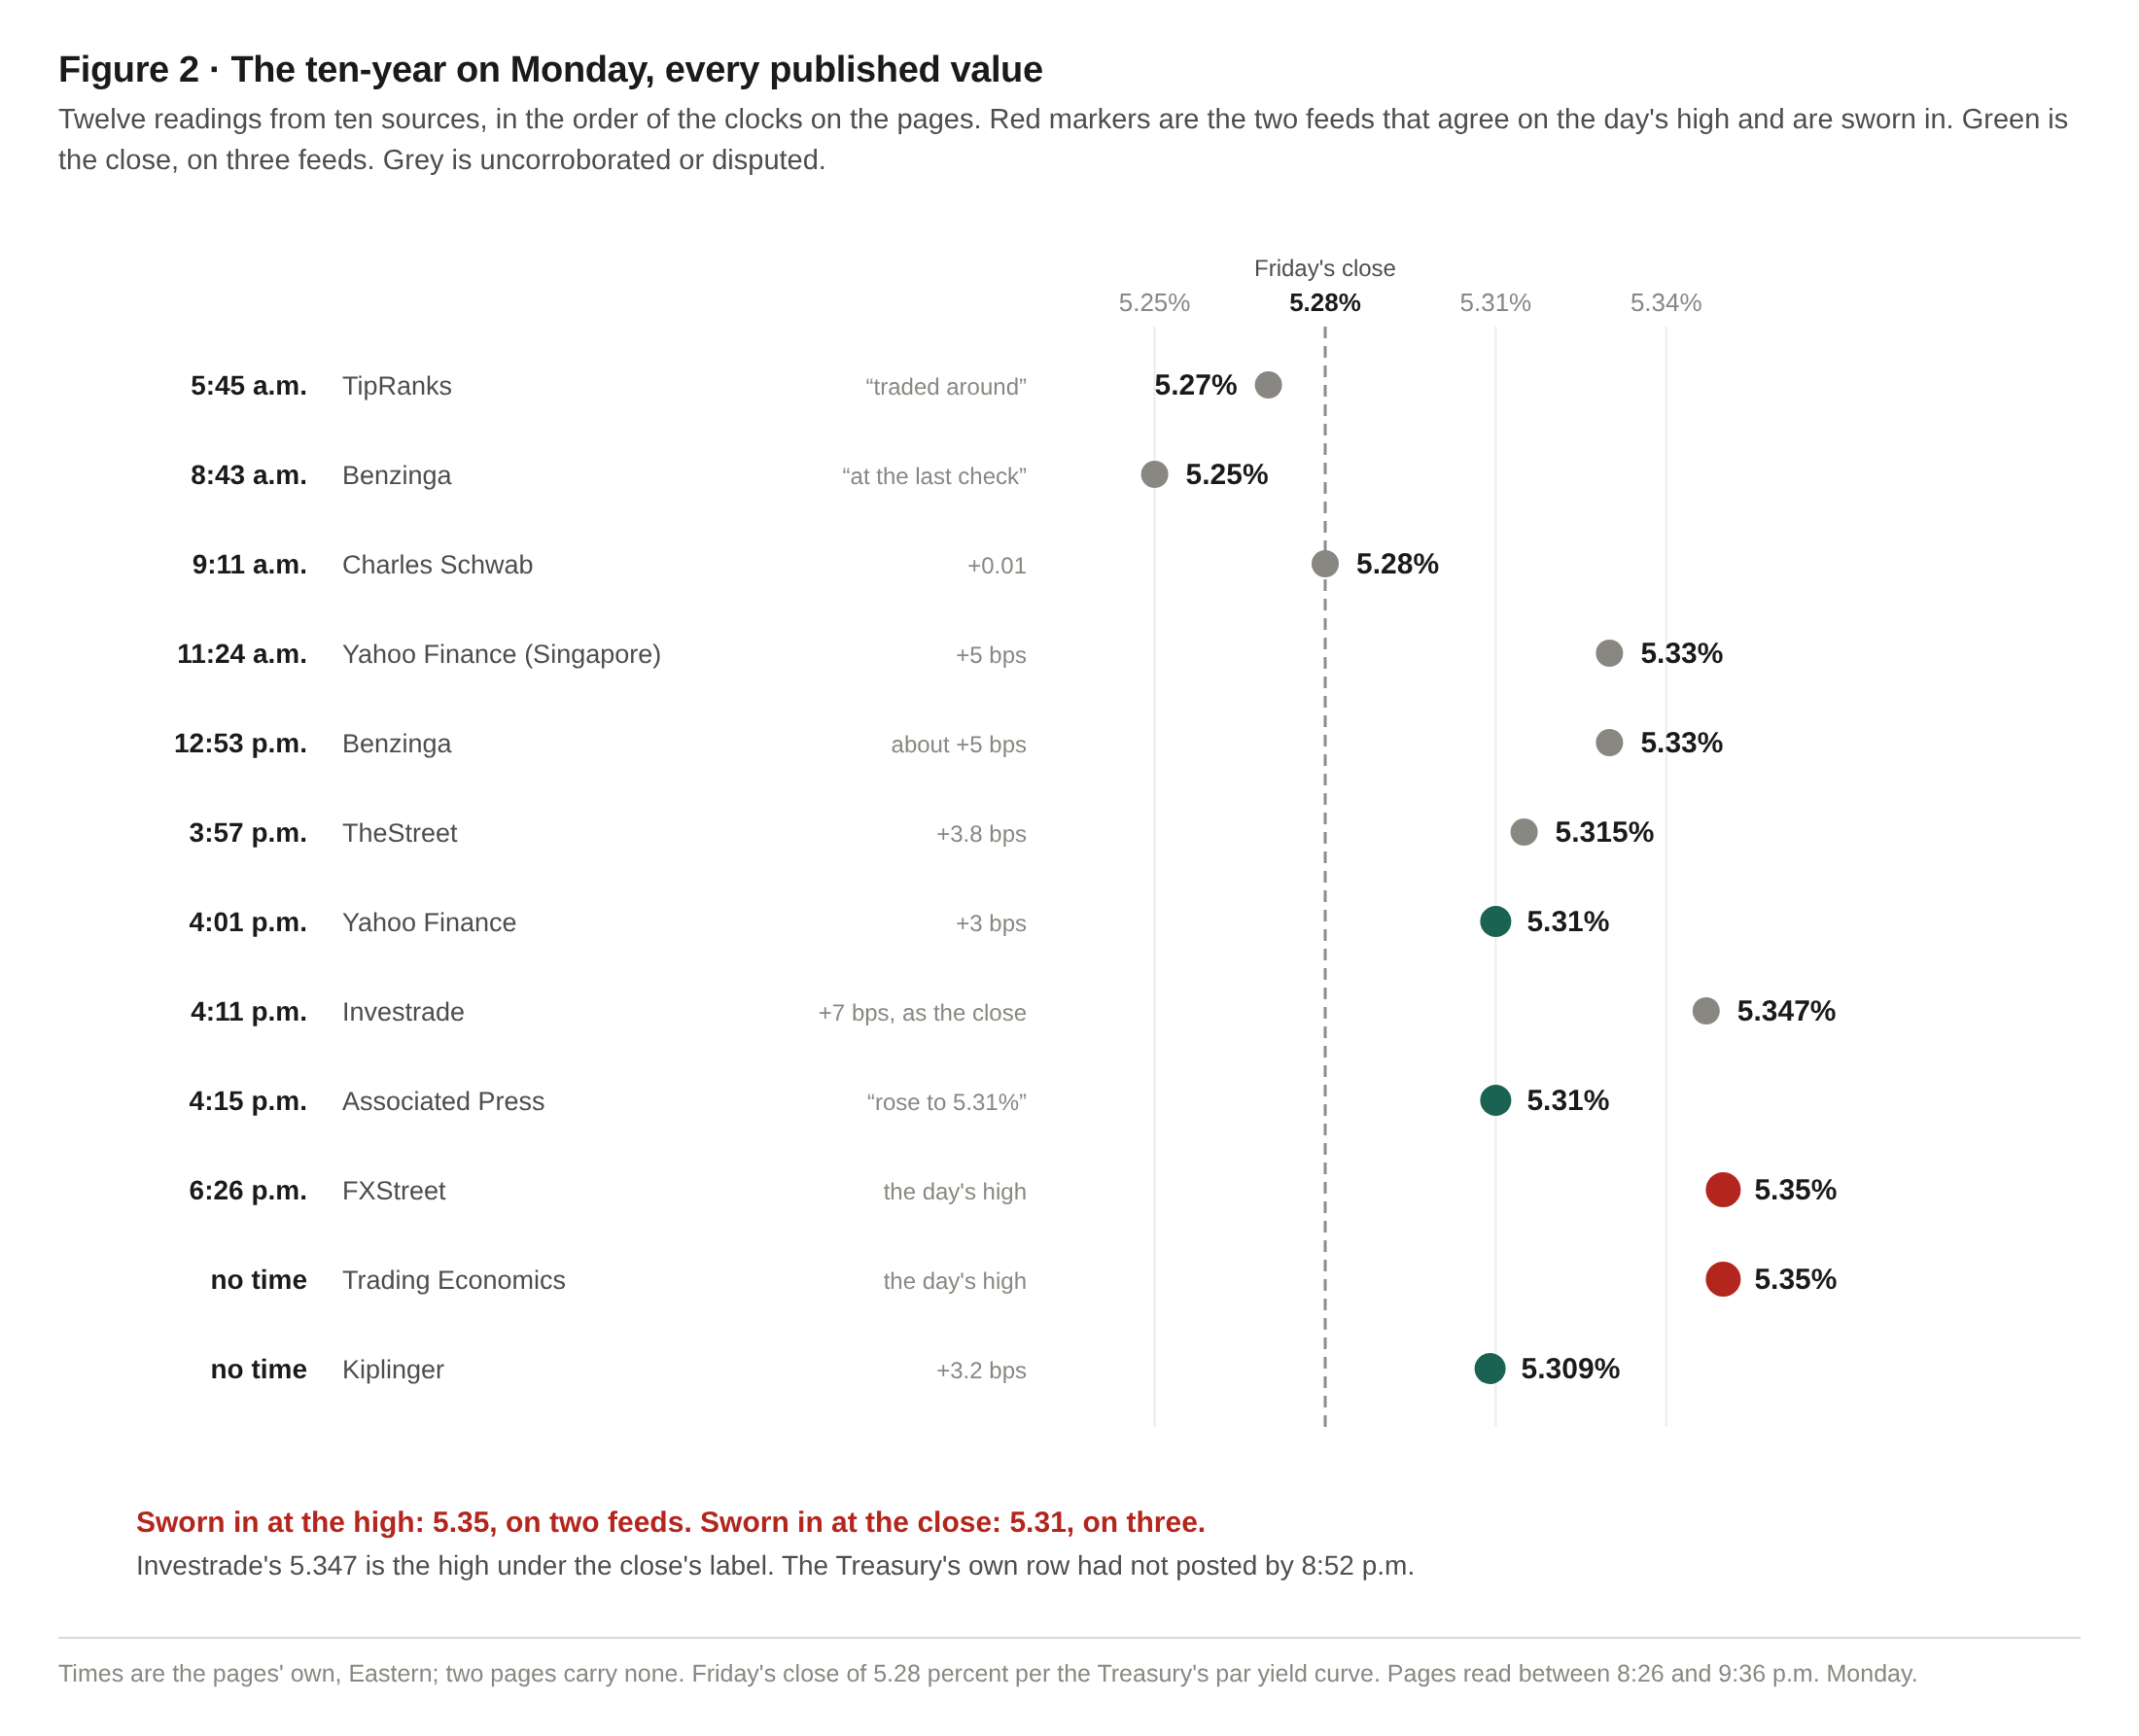
The morning is not sworn. Benzinga at 8:43 a.m. had 5.25 percent. Charles Schwab at 9:11 had 5.28, up 0.01. Friday closed at 5.28, so one of them read a market that had rallied and the other a market that had not moved.
Sworn in at the high: 5.35 percent. Trading Economics ("increased to 5.35%, the highest since April 2002") and FXStreet ("touched 5.35% on Monday, its highest since April 2002"). Investrade's 5.347 rounds to it, and the Associated Press says the yield "almost got to 5.35%."
Sworn in at the close: 5.31 percent. The Associated Press ("to 5.31% from 5.28%"), Yahoo Finance at 4:01 p.m. and Kiplinger at 5.309, up 3.2 basis points. Reuters called it the highest close in two decades. The Treasury's own row for Monday had not been posted when the desk read the table between 8:42 and 8:52 p.m., and that row sets the record.
Not sworn: 5.347 as a close. Investrade's review, stamped 4:11 p.m., says the ten-year "rises 7 bps to 5.347%." That is the day's high wearing the close's label.
The day's change was printed, at one hour or another, as two, three, 3.2, 3.4, 3.8, 4.7, five and seven basis points. The gap between the smallest and the largest is wider than the move.
Wrong tomorrow
Tuesday is the August trade report at 8:30, Vice Chair Bowman at 10:45, a $58 billion three-year auction at 1:00 and Constellation Brands after the close. Eight things to expect.
1. The trade report at 7:30. Investing.com's time, copied by a calendar or a morning note, or Bowman placed at 9:45.
2. A beat and a miss from one deficit. The consensus is in print at $102.0 billion (Trading Economics; Goldman Sachs's list via ZeroHedge), $95.2 billion (Investing.com; investingLive; FX Empire) and $89.8 billion (ActionForex; Avalon Capital). The print between them will be called wider and narrower than expected.
3. The goods deficit under the total's name. July's goods and services deficit was $88.6 billion. The advance goods deficit for August, already published, was $132.6 billion. Expect the larger number called "the trade deficit," or the word "record," which belongs to March 2025's goods deficit.
4. Job openings on a Tuesday that has none. The first Tuesday of the month is a habit. The Bureau published August's openings on 29 September and will publish September's on 3 November.
5. The ten-year record with the wrong year. "Highest since 2007" and "since March 2022" were both in print on Monday. The year is 2002.
6. Monday's changes at Tuesday's open. Trading Economics' index page with 51.23 and 90.94 beside Tuesday's levels, and Tuesday night with a new pair. For Monday's pair, level less change should equal 7,722.72 and 51,176.96.
7. Monday's Treasury rows on Tuesday's card. 24/7 Wall St. has carried the previous day's yields under the current stamp twice running. Monday's rows would read 5.31 for the ten-year, up three.
8. Constellation Brands on the wrong day, against the wrong number. The company reports Tuesday after the closing and holds its call Wednesday at 8:00 a.m.; one preview's headline says, "Reports October 7." Earnings consensus is $3.55, $3.56, and $3.62 a share.
Tuesday night's sheet reports which of these were printed.
Sources and data notes
Every figure carries its feed and the time it was observed. Pages were read on Monday between 8:26 and 9:36 p.m. Eastern, through a reader that relays their text; the quotation on which each entry turns was read at least twice. A linked page shows its state now, not the state read.
Monday's closes. S&P 500 7,773.95, up 51.23; Dow 51,267.90, up 90.94; Nasdaq Composite 27,477.31, up 286.45; Russell 2000 2,847.14, up 14.24: Associated Press via KRMG, stamped 4:15 p.m. The first three match TheStreet at 4:07 p.m. to within four hundredths of a point; its Russell 2000 of 2,853.27 is an early table and is not logged. The range and Friday's 7,722.72: Yahoo Finance. November WTI $89.43 and December Brent $100.32: investingLive and Investrade.
Entries 1 to 3. Yahoo Finance's blog at 10:15 a.m. and 4:01 p.m.; AOL; the ISM release, read on PR Newswire; the Treasury's par curve (ten-year 5.29, 5.24, 5.28 and two-year 4.88, 4.78, 4.83 for 30 September to 2 October) and the H.15; Trading Economics, bonds; Benzinga; Reuters, 1 October.
Entries 4 to 9. 24/7 Wall St.'s closing card and two-year card; Kiplinger; Investrade's preview, mid-morning look and review; Trading Economics, indexes, read 8:27 to 9:08 p.m.; Investing.com, read 9:00 and 9:35 p.m.; Census, BEA and the Board's calendar.
Entries 10 to 15. The Employment Situation; ABC News; Investopedia; Kiplinger; Trading Economics; Breitbart; My Weekly Stock; HDFC Sky; SwingFish; finwire; investingLive.
The forecast. Benzinga; investingLive; Yahoo Finance; Fox Business; CV Research; Dallas Express; Wolf Street. Accenture's close is Benzinga's. Futu's weekly list could not be read.
The ten-year. TipRanks, 5:45 a.m.; Benzinga, 8:43; Schwab, 9:11; Yahoo Finance, Singapore edition, 11:24; Benzinga, 12:53 p.m.; TheStreet, 3:57; Yahoo Finance, 4:01; Investrade, 4:11; Associated Press via TV News Check; Reuters, 5:04; FXStreet, 6:26; Trading Economics and Kiplinger, no time. The 4.7 is TipRanks and the 3.4 investingLive.
Tuesday. Trading Economics; ZeroHedge; investingLive; FX Empire; ActionForex; Avalon Capital; Census, July; Reuters on August goods; the BLS schedule; the Treasury's auction schedule, with $58 billion from secondary notes; Constellation Brands; Benzinga, Zacks and TipRanks for the estimates; Alphastreet's headline, seen in search only.
This desk's arithmetic. 7,787.91 less 7,773.95 is 13.96; over Friday's 7,722.72 the two are gains of 0.84 and 0.66 percent. 51,267.90 less 90.94 is 51,176.96, and 90.94 over it is 0.18 percent. 4.78 plus 0.05 is 4.83. 101.17 plus 1.08 and 100.32 plus 1.93 are both 102.25. 5.277 plus 0.021 is 5.298. 7,781.04 less 51.23 is 7,729.81. 8,000,000 over 29,000 is 276.
Seen and not logged. Four consensus figures for the ISM index (55.0, 55.1, 55.2, 55.7), which are different surveys; and The Motley Fool's ten-year that "rose 0.03%," a unit, not a figure.
The chronicle. 182 at the start of this issue; 197 after tonight's fifteen entries, numbers 185 to 199.