THE ERRATA
The Errata No.8
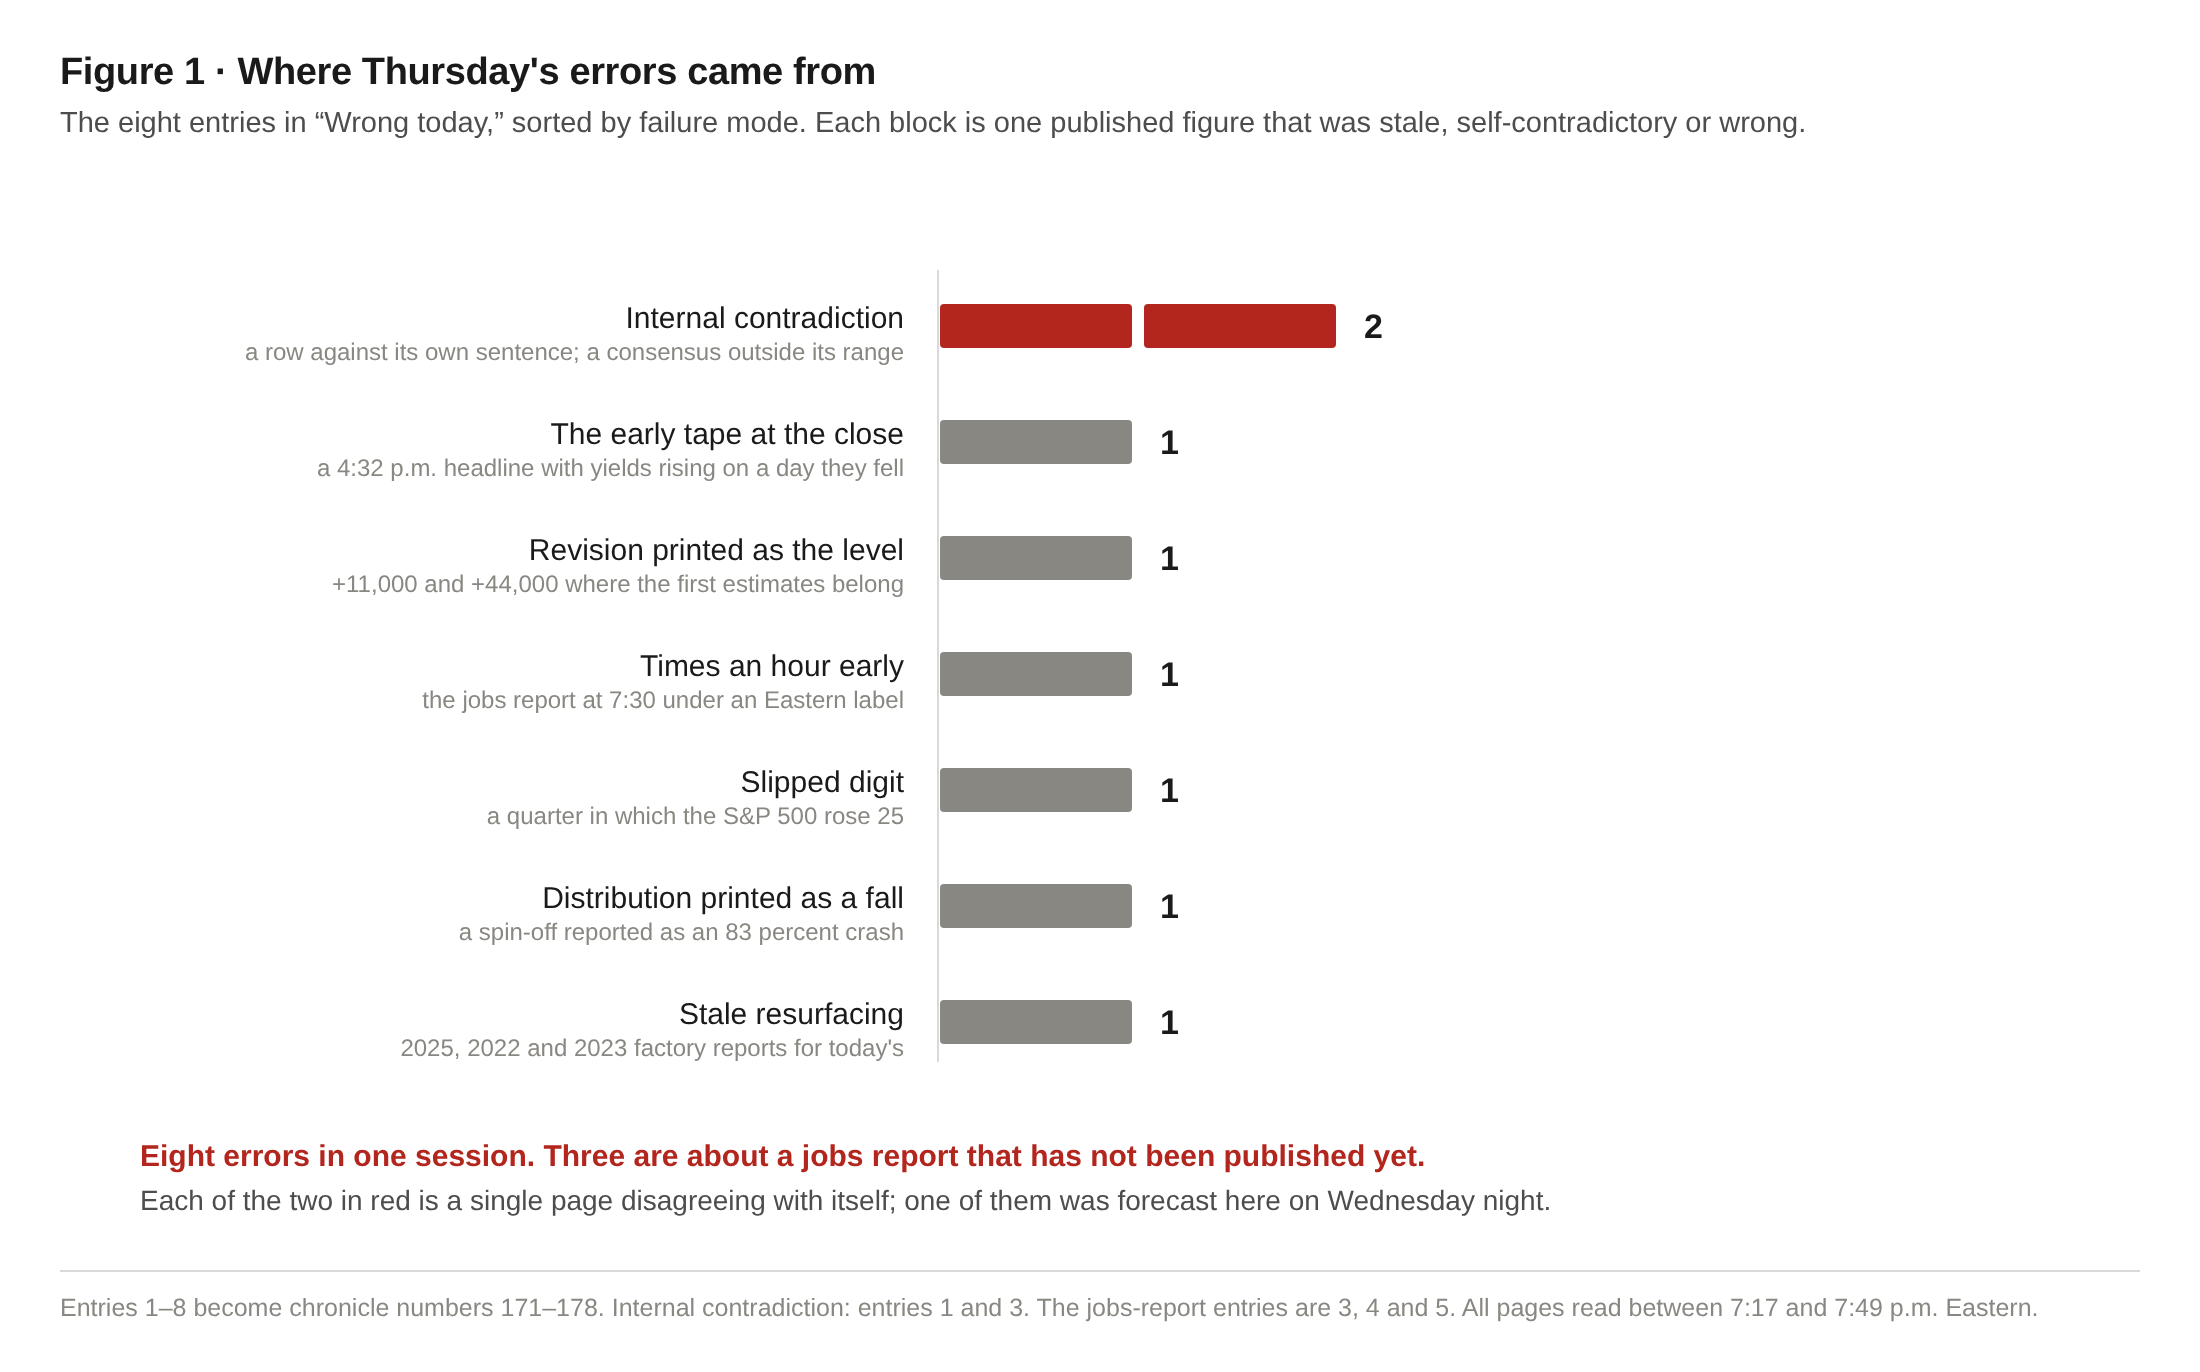
The ten-year Treasury yield touched its highest level since 2002 and then closed lower, yet one closing item still had it rising. Eight entries tonight, three about a jobs report that has not been published. Nine errors named for Friday before they happen, because the day already split in two.
The first session of the quarter reversed itself. The ten-year Treasury yield reached its highest level since 2002 early in the day; the Federal Reserve’s vice chair said the committee may need more time to judge whether further increases are needed, and the yield finished lower than it began. Stocks finished a little higher. This sheet exists for days like this: the early numbers do not leave the page when the afternoon contradicts them.
Eight entries tonight, every page read between 7:17 and 7:49 p.m. Eastern. One was forecast here last night. Three concern tomorrow’s jobs report, which has not happened yet and is already misprinted. The pattern is simple: the day keeps being split between what printed early and what proved true later.
Wrong today
Each entry names the outlet, quotes what it printed, states what was true and says how the gap surfaced.
1. One session’s change beside another session’s level, a fourteenth time. Forecast in No. 7 (item 6), in its morning form. Trading Economics’ United States page, read twice this evening, showed the S&P 500 at 7,677.05 beside a change of 14.91 and 0.19 percent, and the Dow at 50,956.55 beside 20.51, both dated October 1, under a sentence saying the index “rose to 7678 points on October 1, 2026, gaining 0.34% from the previous session.” The changes are Thursday’s cash session to the cent: the S&P 500 closed at 7,666.45, up 14.91, and the Dow at 50,926.56, up 20.51. The levels are contracts trading after the bell. 7,677.05 less 14.91 implies a Wednesday close of 7,662.14; Wednesday closed at 7,651.54. One row says 0.19 percent, and the sentence above says 0.34. Caught by subtracting.
2. A closing story with the morning’s bond market in it. TheStreet’s live blog, in the update stamped 4:32 p.m., was titled “Stocks finish flat on rising Treasury yields,” over the sentence “The 10-year U.S. Treasury yield rose 4 basis points to 5.3338% on Thursday, according to LSEG data, reaching its highest level since April 2002.” The update two minutes earlier said stocks finished “mostly flat despite rising yields.” Yahoo Finance, whose address stamps it 7:25 a.m., already had the ten-year at a 2002 high, and by 2:53 p.m. its own board read 5.24. Then it kept falling. Kiplinger’s close story, stamped 4:11 p.m., has the ten-year “closing down 5.9 basis points at 5.234%,” and a second feed has the close at 5.233. Yields fell on the day, and the bell story says they rose. Caught against two closes.
3. A consensus that sits outside its own range. InvestingLive’s preview of Friday’s payrolls, stamped 5:53 p.m. on its own clock, opens with “Consensus estimate +910K (range +35K to +180K).” Every other preview read tonight sits between 84,000 and 93,000. A consensus cannot be five times the highest estimate that went into it. The likeliest reading is 91 with a zero attached, but the desk does not know that. Caught by reading the range beside the number.
4. The size of a revision printed as the number revised. Kiplinger’s jobs preview, stamped 9:47 a.m.: “And job growth for June (+11,000 to +31,000) and July (+44,000 to +21,000) was upwardly revised, resulting in a combined 55,000 more jobs than previously reported.” As stated, June rose by 20,000, and July fell by 23,000, which is a downward revision and a combined loss of 3,000. The Bureau of Labor Statistics’ August release says June “was revised up by 11,000, from +20,000 to +31,000,” and July “was revised up by 44,000, from -23,000 to +21,000.” The 11,000 and the 44,000 are the revisions; they were printed where the first estimates belong. These months will be revised again at 8:30 tomorrow. Caught by adding, then against the primary document.
5. The jobs report at 7:30. Investing.com’s preview, “Nonfarm payrolls, unemployment rate and hourly earnings due Friday,” published at 2:01 p.m., lists all three under “7:30 AM ET.” The Bureau’s own release says the September report “is scheduled to be published on Friday, October 2, 2026, at 8:30 a.m. (ET).” It is the failure of entry 163 on a new page: the same outlet listed Thursday’s claims at 7:30 and the ISM index at 9:00. Last night’s forecast expected other calendars to copy those times; the source repeated itself instead. Caught against the agency’s schedule line.
6. A quarter in which the S&P 500 rose 25. Zacks’ morning recap, syndicated by Yahoo Finance at 3:36 a.m.: “Third-quarter 2026 was also mixed for U.S. stocks. The S&P 500 and the Nasdaq Composite rose 25 and 2.5%, respectively.” Investrade’s table puts the S&P 500 at 2.0 percent for the quarter, 2.03 on this desk’s arithmetic last night. The Nasdaq’s figure and the Dow’s are right, and so are the same figures for September. One digit, in the one number a reader would quote. Caught against a second feed.
7. A spin-off printed as a crash. Stocktwits, syndicated by Yahoo Finance at 10:45 a.m.: “Corteva’s Market Cap Tumbles By Over $42B Today – CTVA Stock Hits Record Low,” with “Shares of Corteva (CTVA) crashed 83% to an all-time low on Thursday” and “CTVA shares have slumped around 81% so far in 2026.” TheStreet at 10:13 a.m.: Corteva “tumbled 81.75%.” On Thursday, Corteva handed each shareholder one share of Vylor, its seed business, for every Corteva share. Corteva closed at $12.57 against $77.65 on Wednesday; Vylor ended the day at $68.26 on one feed and “near $69” on another. Together, the two are $80.83, 4.1 percent more than Wednesday’s single share, measured on the combined basis this desk uses. Both pages name the spin-off. Neither adds the two prices, and the record low and the 81 percent year exist only if you ignore the distribution. Two outlets, one event, counted once. Caught by adding.
8. Three old factory reports for today’s. Searches this evening for the September 2026 ISM manufacturing index returned Trading Economics’ “US Manufacturing Sector Remains in Contraction: ISM,” and FXStreet’s “ISM Manufacturing PMI declines to 50.9 in September vs. 52.2 expected” and “declines to 46.7 in October vs 49 expected,” all reading as current. Today’s reading was 54.5, and the Institute’s release says manufacturing “expanded in September for the ninth consecutive month.” They are dated October 1, 2025, October 3, 2022 and November 1, 2023. Correctly dated at source; nothing where they surfaced said so. Caught by the date strings and the level.
The forecast, scored
No. 7 named eight errors for Thursday. One occurred as named, one occurred in a neighbouring form, five did not occur and one is unresolved.
Occurred. Item 6, the index page pairing Wednesday’s changes with Thursday’s levels at the open. The Morning Brief read it on Trading Economics between 9:37 and 9:39 a.m. It was the pairing already logged Wednesday night as entry 162, so it added nothing to the count. Tonight’s pairing is new and is entry 1 above.
Occurred, neighbouring form. Item 7, September and the quarter swapped or stale. Neither form was found. A wrong quarter was: Zacks’ 25, entry 6 above. Its September figures were right, as were Investrade’s for both periods.
Did not occur. Item 1, other calendars carrying claims at 7:30 and the ISM index at 9:00: searched, not found; Investrade’s calendar had 8:30 and 10:00. Item 2, inflation “cooled from 3.7”: not found; TheStreet’s 9:53 a.m. item on the Minneapolis Fed’s president was headlined “Despite Cooler PCE Data” and measured the core rate against forecasts, not against July. Item 3, the two factory indexes as one: Yahoo Finance printed S&P Global’s 55.9 and the ISM’s 54.5 as two indexes. Item 4, claims measured from the four-week average: not found; the Labor Department has 197,000, down 1,000 from a revised 198,000. Item 5, Brent’s roll printed as a five-dollar fall: TheStreet and Investrade both measured December against December.
Unresolved. Item 8, the ten-year’s record a day stale. Zacks wrote that Wednesday’s touch of 5.3 percent marked the “highest level since June 2007”; Investrade had called the same touch the highest since May 2002. Which is right depends on where the yield peaked in June 2007 on the series each used, and the desk could not establish that. No outlet reported the yield closing above 5.30.
Two of last night’s consensus figures, 54.8 for the ISM index and 201,000 for claims, appeared in no outlet read today. The figures in print were 55.0 and 200,000.
The one number, reconciled
The ten-year Treasury yield was the number of the day, because it was two numbers. Here is every value published for it, in the order the desk reads them. The point is not the range alone, but the split between the intraday high and the close.
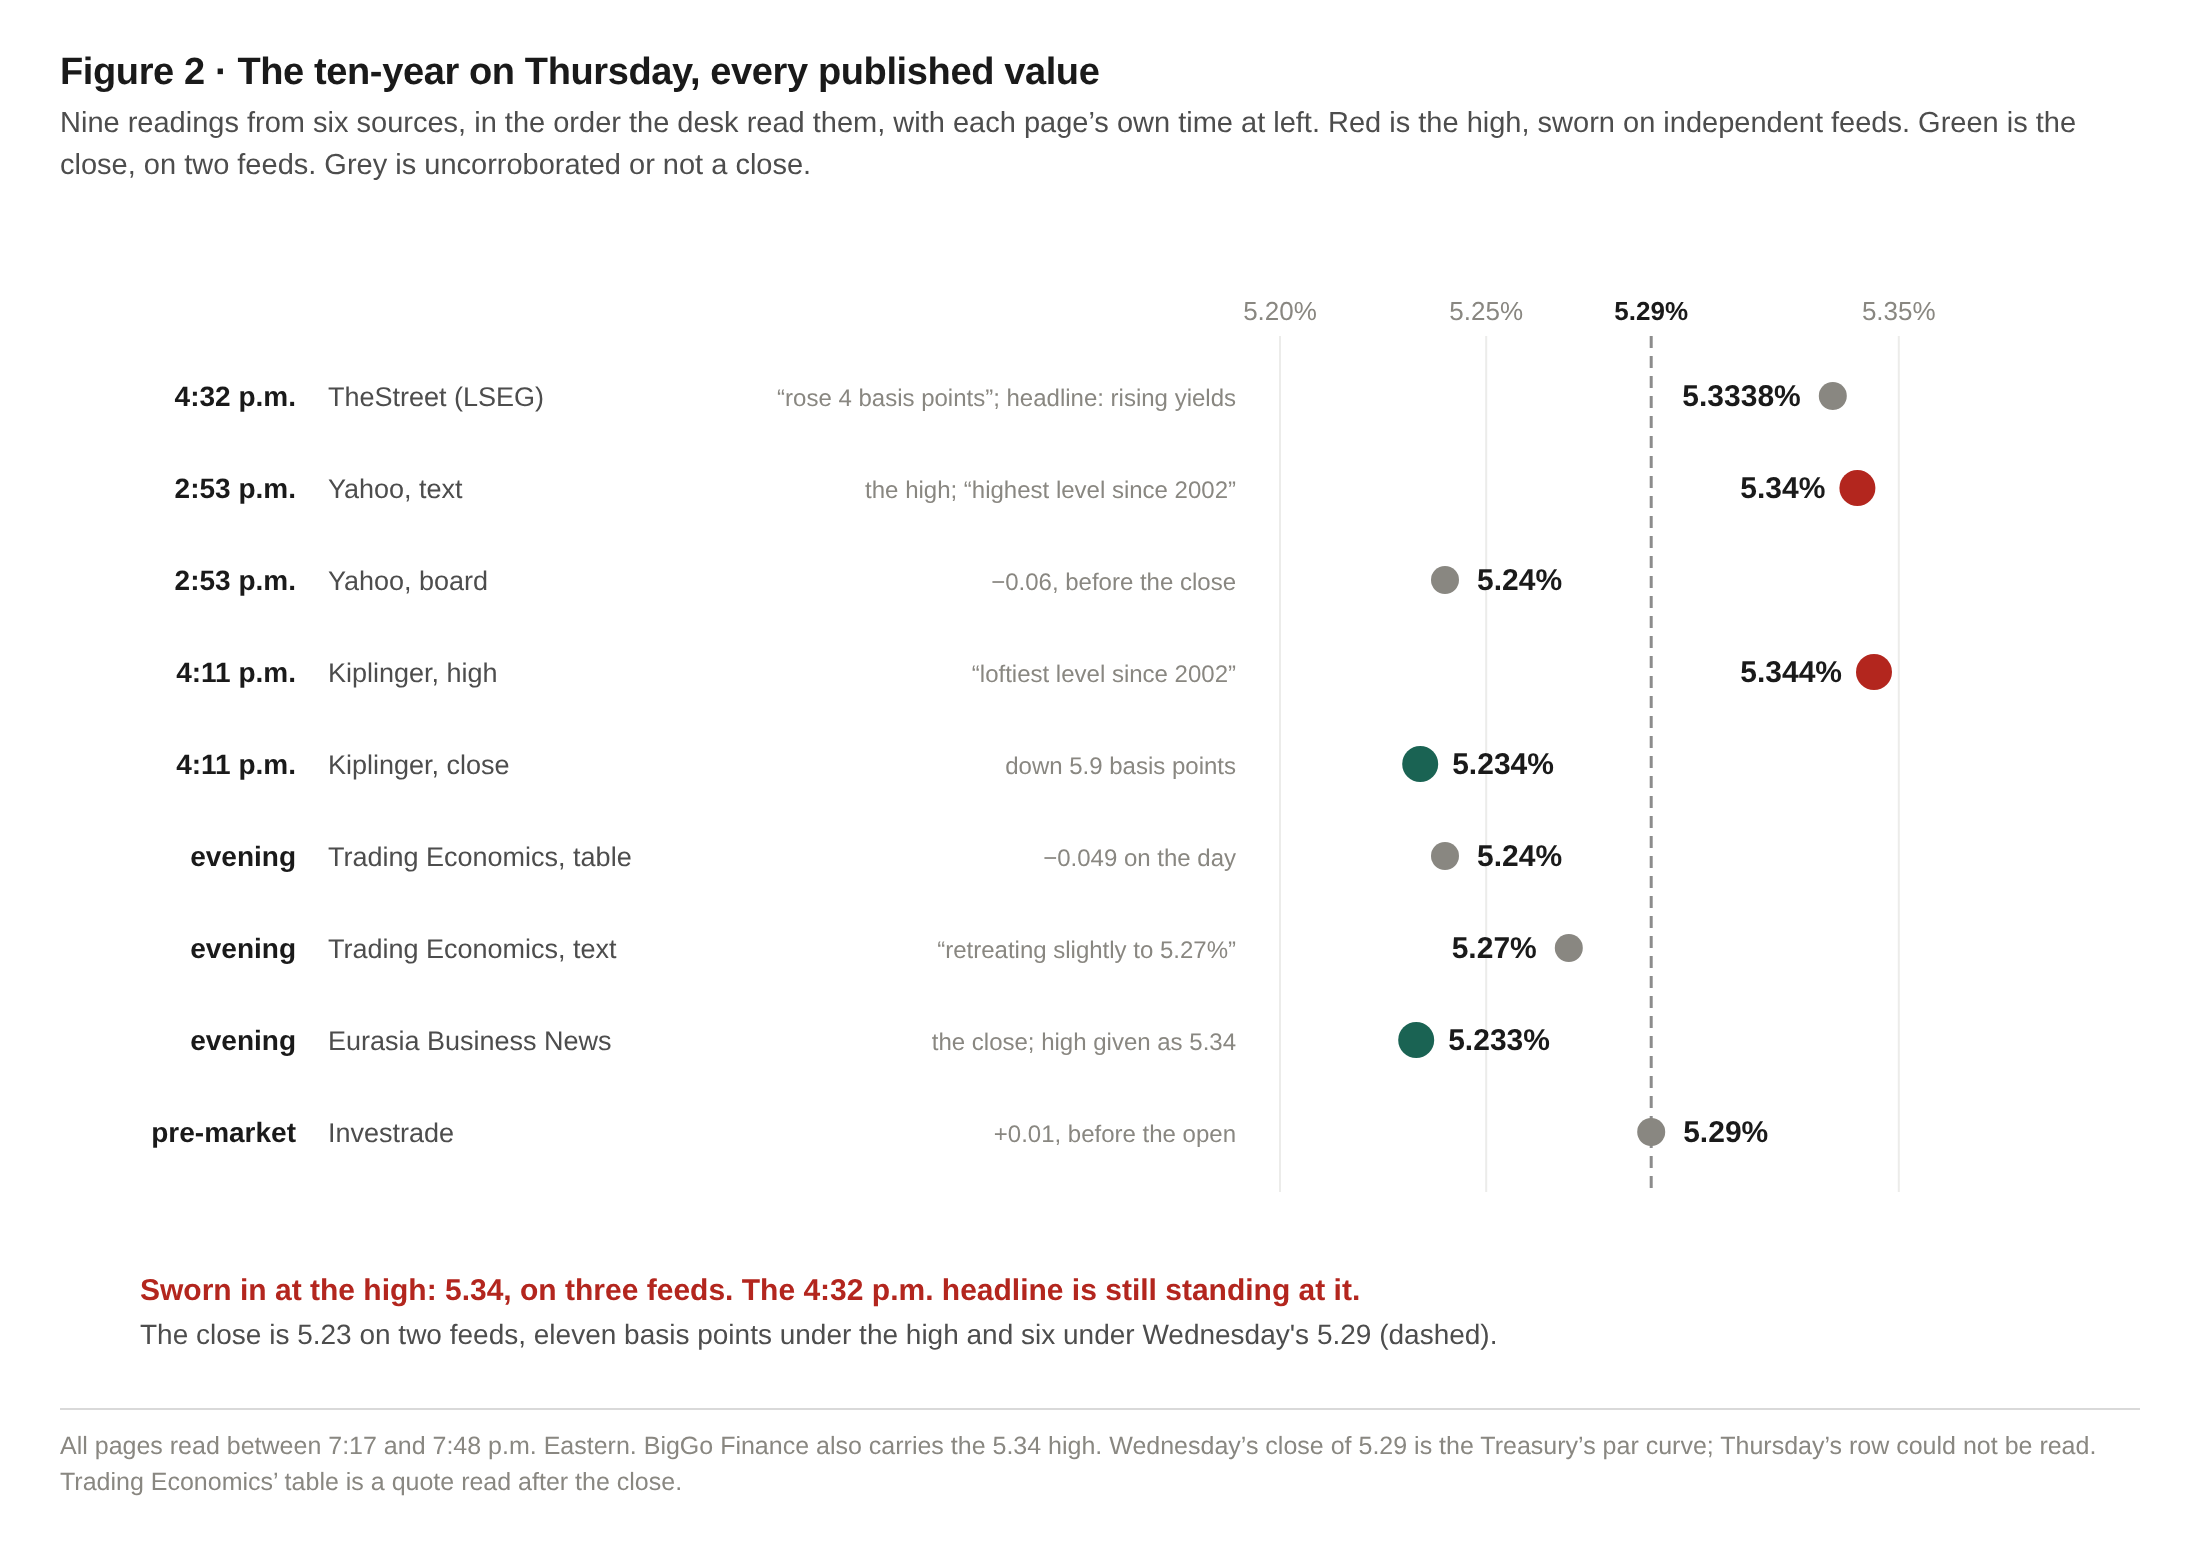
Sworn in at the high: 5.34 percent. Yahoo Finance’s live blog, Kiplinger (5.344) and BigGo Finance all carry it, each placing the last such level in 2002. TheStreet’s 5.3338, from LSEG, belongs to the same climb.
Sworn in at the close: 5.23 percent. Kiplinger at 5.234, down 5.9 basis points, and Eurasia Business News at 5.233. Yahoo Finance’s board read 5.24 at 2:53 p.m., before the closing, and Trading Economics’ table this evening, whose own narrative above it says the yield retreated “slightly to 5.27%.” Two boards read 5.24. The Treasury’s par curve, which would settle it, could not be read past July 7 through the desk’s reader. Both values are printed; neither is averaged.
From high to close, it fell eleven basis points in one session. The closing record still belongs to Wednesday, at 5.29 on the Treasury’s curve. Thursday set an intraday high, then gave back more than Wednesday added. A reader who saw only TheStreet’s headline has the day backward.
The index closes are sworn on the Associated Press and BigGo Finance: S&P 500 7,666.45, Dow 50,926.56, Nasdaq Composite 26,871.60. Oil is not sworn. BigGo has Brent at $102.31 beside WTI at $92.87 for the day, one feed; TheStreet at 7:07 a.m. had Brent at $100.60 beside WTI at $92.28.
Wrong tomorrow
Friday is the September jobs report, at 8:30. Nine things to expect.
1. A beat and a miss from one number. The consensus in print tonight is 84,000 (Schwab), 89,000 (Investing.com), 93,000 (Kiplinger) and “+910K” (investingLive). A print between those figures will be called both. Watch for a headline that names no consensus, and for 910,000 surfacing anywhere else.
2. The report at 7:30. Investing.com’s time, copied by a calendar or a morning note. It is 8:30.
3. August measured from a number that no longer exists. August’s 162,000 and July’s 21,000 are revised tomorrow. “Slowed from 162,000” printed after the revision uses the withdrawn figure. Watch too for Kiplinger’s garbled revisions, first estimates of +11,000 and +44,000, repeated.
4. Private payrolls as the headline. Investing.com has 82,000 private against 89,000 total. One will be printed under the other’s name.
5. Wages, monthly for annual. Consensus is 0.3 percent for the month and 3.2 percent for the year, from 3.1. Expect “rose 0.3 percent from a year earlier,” or the annual rate called unchanged.
6. A fifteenth time. Thursday’s changes, 14.91 and 20.51, beside Friday’s contract levels on Trading Economics at the open. Level less change should equal 7,651.54 and 50,906.05.
7. Thursday’s bond market told backwards. “Yields rose Thursday” in a Friday-morning recap, on the strength of the 5.34 high, or “closed at a 24-year high.” The close was about 5.23, down six basis points, and the record close was Wednesday’s 5.29.
8. The morning’s movers at the week’s end. Accenture’s 21.41 percent from 10:13 a.m., or “more than 20 percent,” in a recap; it closed up 15.78 percent at $212.30. And Corteva in a list of the week’s biggest losers at minus 84 percent, without Vylor.
9. Two odds for one meeting. The chance of an increase on October 28 was 37 percent in Schwab’s note and 30 percent in investingLive’s, the same day, neither with a time. After 8:30, there will be a third, described as a move from whichever the writer saw.
That is the forecast. Friday night’s Errata scores it against what was printed, as reporting and not as a grade.
Sources and data notes
Every figure carries its feed and the window in which it was read, Eastern. The desk clock read 7:17, 7:29, 7:37, 7:48, and 7:49 p.m.; pages are stamped to the window between two readings. Pages reach the desk through a reader that relays their text. The quotations on which entries 1 to 4 and 6 turn were read twice; those in entries 5, 7 and 8 once.
Thursday’s close. S&P 500 7,666.45 (+14.91), Dow 50,926.56 (+20.51), Nasdaq Composite 26,871.60 (+10.53), Russell 2000 2,806.63 (+9.76) per the Associated Press via KRMG, 7:17–7:29; the first three also per BigGo Finance, 7:37–7:48, and rounded in Kiplinger’s close story, stamped 4:11 p.m. Wednesday’s closes of 7,651.54 and 50,906.05 per Investrade’s morning preview and Schwab.
Entry 1. Trading Economics, United States, read 7:17–7:29 and 7:37–7:48.
Entry 2 and the ten-year. TheStreet’s live blog, updates stamped 4:30 and 4:32 p.m., read three times between 7:17 and 7:37. Yahoo Finance’s live blog, board stamped 2:53 p.m. (5.24, −0.06; high 5.34), 7:17–7:29; its pre-market piece, “Stock futures mixed as 10-year Treasury yield hits 2002 high”, seen in search and timed by its address, not opened. Kiplinger as above (high 5.344; close 5.234; thirty-year 5.693 and 5.603). Trading Economics’ bond page (table 5.24, −0.049; narrative 5.27), 7:17–7:29. Eurasia Business News (5.34; 5.233), 7:17–7:29. Investrade’s preview (5.29, +0.01, before the open). The Treasury’s par curve returned no row after July 7 to the reader. Wednesday’s 5.29 per the Chronicle’s audit block of this morning.
Entries 3 to 5. InvestingLive’s preview, read twice, 7:29–7:37. Kiplinger’s jobs preview, stamped 13:47 UTC, read twice, 7:37–7:48. Investing.com’s preview, 7:29–7:37. The Bureau of Labor Statistics’ August release, 7:48–7:49. Schwab’s 84,000 as above.
Entries 6 to 8. Zacks via Yahoo Finance, read twice, 7:29–7:37. Stocktwits via Yahoo Finance, 7:37–7:48; Corteva’s close per stockanalysis.com; Vylor per MarketChameleon and Pomegra, 7:48–7:49. Trading Economics’ item of October 2025, opened 7:29–7:37; FXStreet’s 2022 and 2023 pieces, seen in search and dated by their addresses, not opened. Today’s index per the Institute’s release and FXStreet.
The scoring. Claims per the Labor Department’s release, 7:29–7:37. Accenture’s close per stockanalysis.com. November Brent’s expiry is $103.50 on The Rio Times against the $103.53 printed in No. 7; a three-cent difference between feeds, not logged.
This desk’s arithmetic. 7,677.05 − 14.91 = 7,662.14; 50,956.55 − 20.51 = 50,936.04. Kiplinger’s revisions as printed: (31,000 − 11,000) + (21,000 − 44,000) = −3,000. Corteva: $12.57 + $68.26 = $80.83; $80.83 ÷ $77.65 = 1.041. The ten-year: 5.344 − 5.234 = 0.110.
The Chronicle. 168 at the start of this issue; 176 after tonight’s eight entries, numbers 171 to 178.