The Errata 07
This issue argues that the market's errors recur as errors of timing, level, or comparison. An inflation report measured against a revised July, a Nasdaq printed two thousand points too high, and a rally still running at five o'clock that had ended by four: these are the kinds of errors that recur here. Ten entries, yesterday's forecast scored a day late, and eight errors named for Thursday.
Correction. The Errata, No. 6, counted seven Federal Reserve speakers for Tuesday and named Governor Cook among them. There were six. The Board's calendar for 29 September lists Bowman, Barr and Waller; Newsquawk's primer adds Goolsbee, Musalem and Williams. The Tuesday Brief's second edition carried the same seventh name. My two readings of Cook's schedule disagree: one shows a speech page dated Monday and a calendar entry for Wednesday at 3:25 p.m., but neither puts her on Tuesday. The forecast built on that count is scored below; none of its three forms needed her.
Wednesday closed the quarter, bringing an inflation report whose basis was rewritten on the morning it was published. Most of the day's coverage measured the new number against the revised basis. That is the first entry.
This issue is late. The run that builds it stalled for two hours after the close, and every observation below was made between 9:21 and 9:50 p.m. Eastern. No Errata ran on Tuesday, so No. 6's forecast is scored here, a day late. That delay matters because the errors recur as errors of timing, level, or comparison. This issue tracks that pattern throughout.
Wrong today
Ten entries. Six are Wednesday's. Four are Tuesday's, found while scoring the forecast.
1. An inflation report that "slowed" only against a July that no longer exists. The Bureau of Economic Analysis published August alongside its annual update, which revises the series back to January 2021. July's annual rates, first printed on 26 August as 3.7 percent and 3.3 percent for the core, are now 3.4 and 3.0 percent, per FXStreet and, for the core, Investrade. The consensus of 3.7 that most outlets measured against was July's old number, not the revised basis. August's are 3.4 and 3.0. Charles Schwab's 9:13 a.m. note was headlined "Inflation Growth Slows, Sending Stocks Up Early." The annual rate did not move, and the monthly rate rose to 0.3 percent from a revised 0.1 percent. Kiplinger said it in a sentence: the monthly increases "accelerated from July," and the lower annual figures "were a result of the BEA's adjustment." Caught against the revised basis.
2. A Nasdaq two thousand points too high, and a September that ended on Tuesday. The Nasdaq closed at 26,861.06, the Associated Press reported. Measured from the 31 August closes, the S&P 500 lost 0.45 percent in September and the Dow 4.29; the S&P's month stood at 0.2 percent at Tuesday's close. The same story has the headline PCE index up 0.2 percent on the month, where the BEA's release says 0.3. Kiplinger's close story, stamped 4:15 p.m.: the Nasdaq Composite
3. Noon's tape in a five o'clock story. The Motley Fool published "Stock Market Indexes Rally on Inflation Data, Though the Dow Sat It Out" at 5:03 p.m. Its body says the Nasdaq "climbed 1.1% as of 12:05 p.m. ET," the S&P 500 "added 0.6%" and the Dow "sat exactly flat." The tickers the page prints beside those names read +0.24, −0.25 and −0.86 percent, which are the closes. The rally in the headline was an hour gone when the piece appeared—caught by reading the tickers against the prose.
4. Wednesday's change beside Thursday's level, a thirteenth time. Trading Economics' United States page, read at 9:27 and again at 9:44 p.m., showed the S&P 500 at 7,677.36 beside −19.30, −0.25 percent, and the Dow at 51,036.20 beside −443.87, both dated 1 October. The sentence above the table says the index is "gaining 0.33%." Those are Wednesday's cash changes to the cent, per the Associated Press, beside Thursday's contract levels: 7,677.36 plus 19.30 is 7,696.66, and Tuesday's close was 7,670.84. Caught by adding.
5. Tomorrow's releases, an hour early. Investing.com's preview, published at 2:00 p.m., lists "7:30 AM ET - Initial Jobless Claims," "8:45 AM ET - Manufacturing PMI" and "9:00 AM ET - ISM Manufacturing PMI." Every morning release on the list sits an hour early under an Eastern label. Kiplinger's calendar has claims at 8:30 Eastern, the S&P Global index at 9:45 and the ISM's at 10:00, the same hour by which this desk, copying the same outlet, misplaced Tuesday's Fed speakers—caught against a second calendar.
6. Last year's close, to the day. A search for Kiplinger's Wednesday close story returned "Stocks Close September on a High Note" first. It is dated 30 September 2025, with the S&P 500 at 6,688 and the Dow at 46,397. A search for September's Conference Board index returned FXStreet's "dropped to 94.2 in September," also 2025; Tuesday's reading was 81.9. Correctly dated at source, nothing where they surfaced said so; caught by the level against the session.
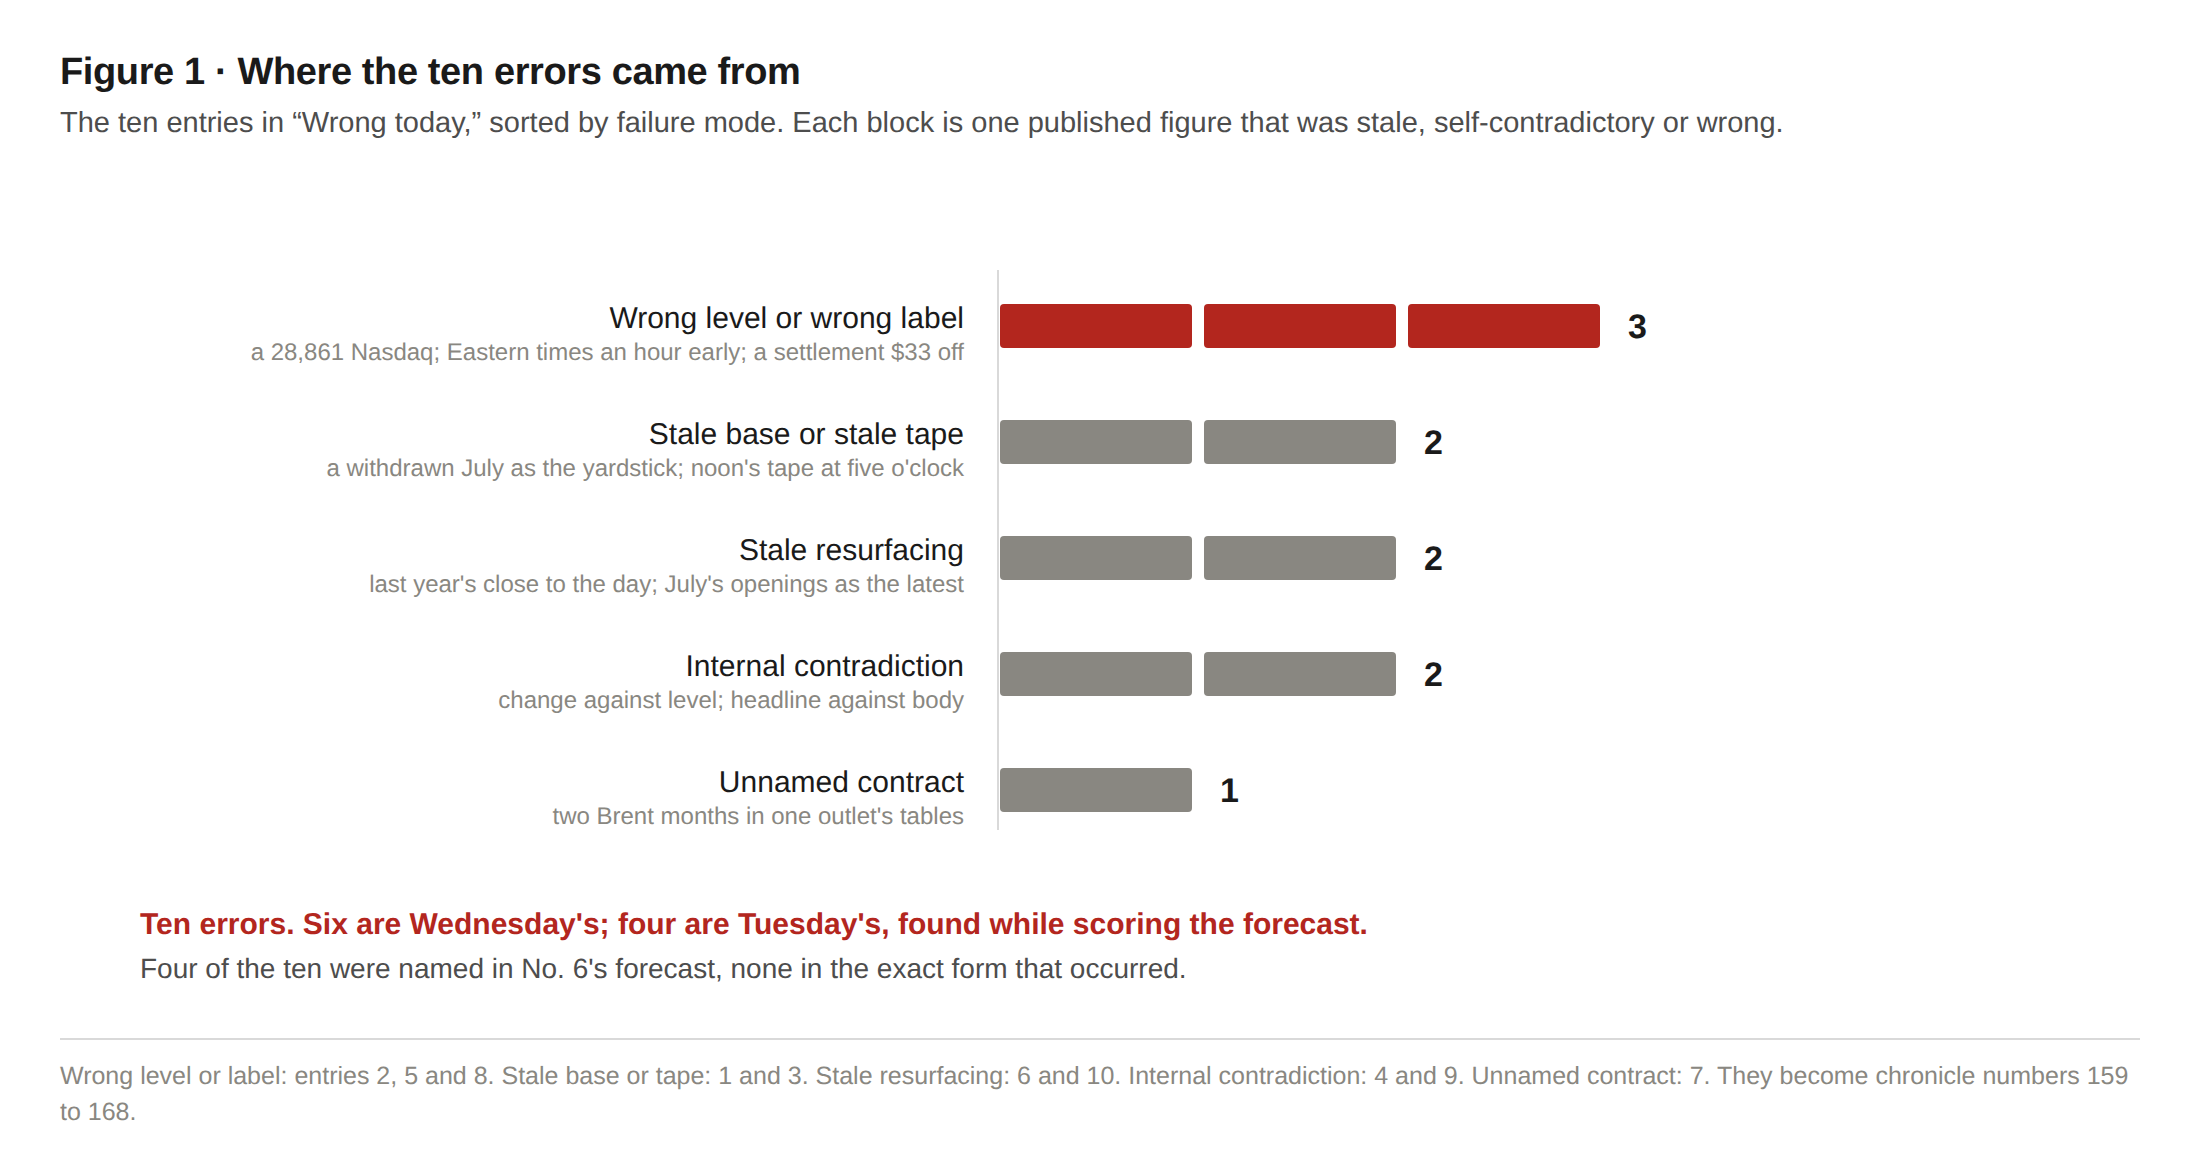
7. Brent's roll, read as a fall. Forecast in No. 6 (item 4). Investrade's three Tuesday tables carried Brent at 105.12 before the open, 96.35 at mid-morning and 102.59 at the close, beside WTI at 92.33, 90.79 and 89.38. No table names a contract. The first and third are the November contract, which settled at $102.59; the second is December, which settled at $96.16, per Bloomberg's report on Rigzone. Brent drops $8.77 between the first two, while WTI drops $1.54. Kiplinger's Tuesday story did name one, wrongly: "Front-month Brent crude oil futures, the global benchmark, dipped 1.9% to $95.95." The front month was November. One roll, two outlets, counted once. Caught by the contract basis.
8. A gold settlement thirty-three dollars from the settlement. Forecast in No. 6 in a neighbouring form (item 6). Investrade and 24/7 Wall St. both have December gold settling on Monday at $4,168.40, down $152.80, or 3.54 percent. TheStreet, at 10:07 p.m. Tuesday: "December gold futures settled 3.52% lower at $4,135.40 an ounce on Sept. 28." I could not establish which contract $4,135.40 belongs to—caught against two feeds.
9. A September gain printed after it was gone. Forecast in No. 6 in a neighbouring form (item 8). 24/7 Wall St., at 9:00 a.m. Tuesday: "SPY gained 1% through September 2026 and is up 13% YTD." Its own body gives 0.82 percent "through a.m. trading on Sept. 28" and 12.38 percent, which does not round to 13. By Monday's close the S&P 500 stood at 7,683.69 against 7,686.14 on 31 August, down 0.03 percent for the month, seventeen hours before the piece appeared. Caught by reading the body, then subtracting from the monthly basis.
10. July's job openings as "the latest." Forecast in No. 6 (item 2, second form). FedRateCalc's page, titled "Latest JOLTS Report: July 2026," says "the latest JOLTS report showed 7.271 million job openings in July 2026" above a schedule marking August's report as released on 29 September. A search for Tuesday's August report returned that page. The Bureau of Labour Statistics reported August at 7.079 million and revised July to 7.335 million. A calculator site, not a newsroom, and logged as such. Caught against the primary document.
The forecast, scored.
No. 6 named eight errors for Tuesday. Four occurred, none in the exact form named. Three did not. One cannot be settled. The score shows the same problem throughout: the forecast often caught the right subject but the wrong moment or measure. This issue's point is simple: the market's errors recur as errors of timing, level, or comparison. This score is the proof.
Occurred. Brent's roll (item 4) is entry 7; the step shows only when one outlet's notes are read in order. Gold's Monday fall in more than one size (item 6) is entry 8, though none of the four sizes named was found. September's performance printed before September ended (item 8) is entry 9; the CoinCentral figure named was not repeated. The July openings report surfacing as current (item 2) is entry 10, the weaker of its two forms: every newsroom read measured August from the revised 7.335 million.
Did not occur. Two consumer confidences treated as one (item 1): the Conference Board's 81.9, down from a revised 88.6, was kept apart from Michigan's 48.1 wherever both appeared. The consensus of 90.1 that No. 6 printed appeared nowhere else; outlets carried 89.0, 89.2 and 90. A Fed speaker's line misattributed, re-dated or set beside "4%" alone (item 3): not found, and Williams said on Tuesday itself, per Reuters, that "one further upward adjustment" may be appropriate late this year. The ten-year measured from the wrong base (item 7): Kiplinger and Investrade both measured from 5.242, the Associated Press from 5.24.
Unresolved. Whether Monday's changes were still on Trading Economics' page after Tuesday's close (item 5). Nobody at this desk read it that evening.
The one number, reconciled
The ten-year Treasury yield, across two closes.
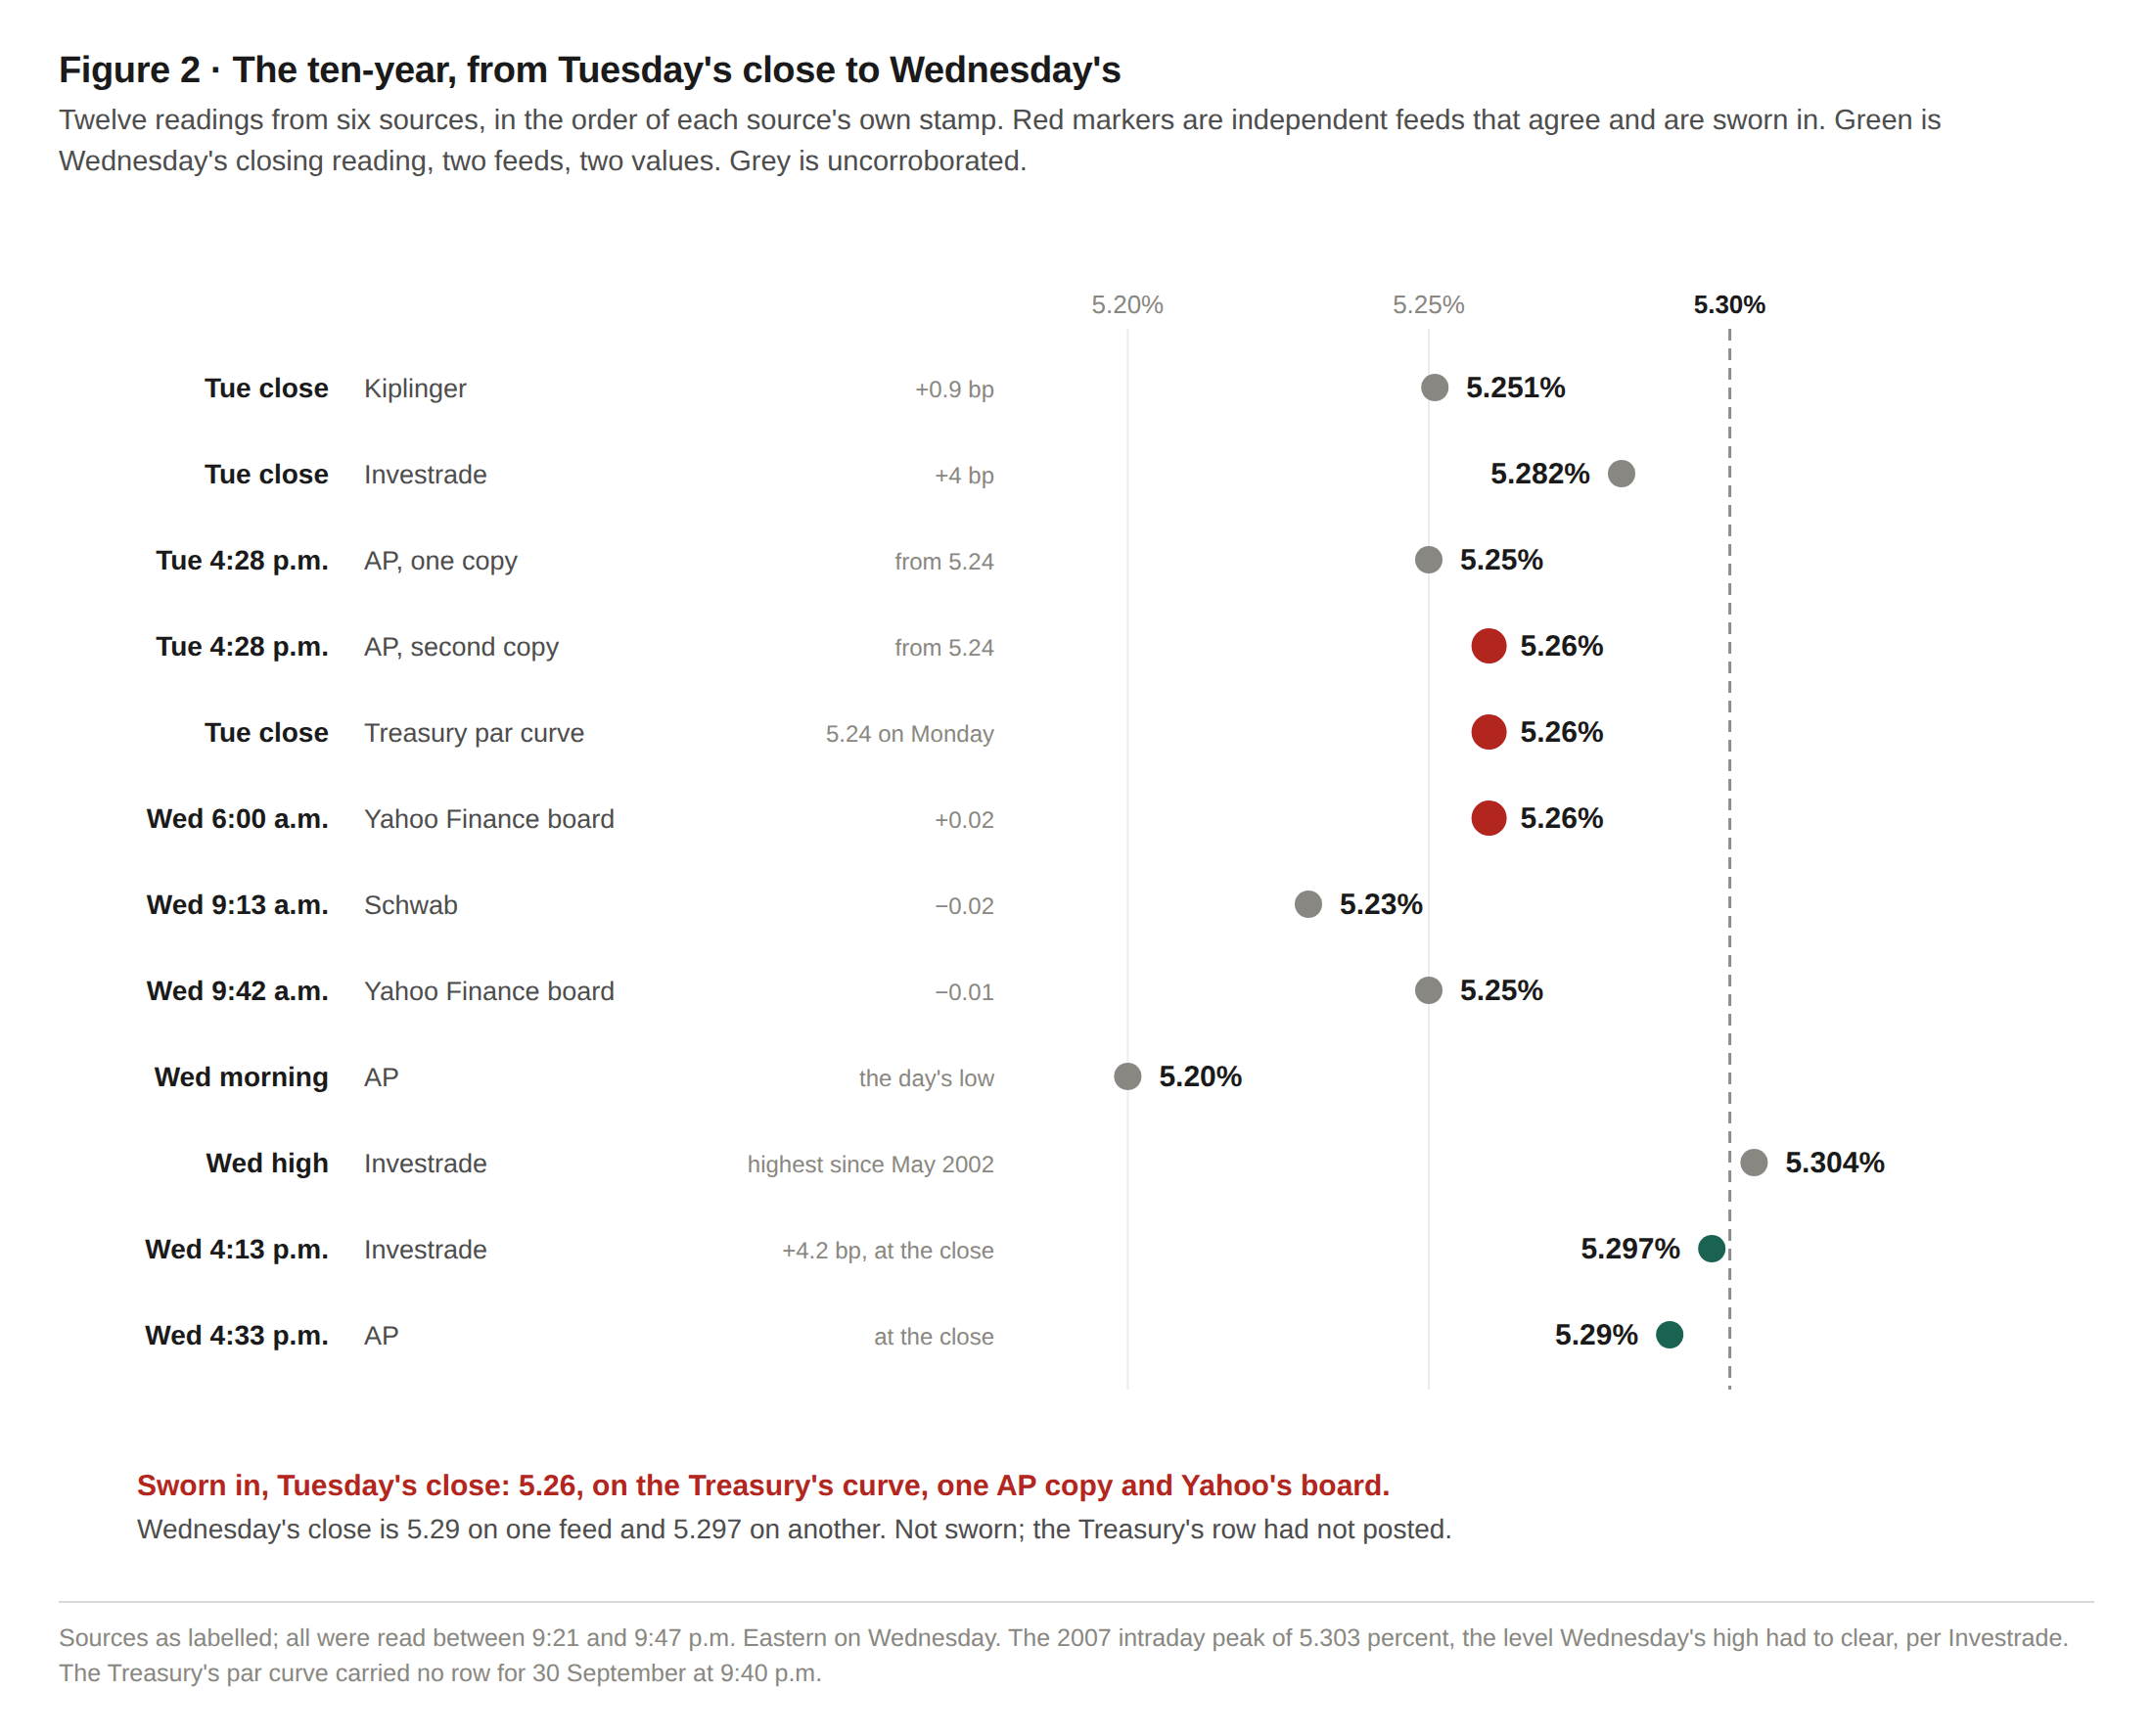
Sworn in, Tuesday's close: 5.26 percent. The Treasury's par curve, one copy of the Associated Press's close story, and Yahoo Finance's board at 6:00 a.m. Wednesday. That settles what the morning Brief left open between Kiplinger's 5.251 and Investrade's 5.282. A second AP copy under the same 4:28 p.m. stamp says 5.25.
Wednesday's close, not sworn. Schwab had 5.23 at 9:13 a.m. and Yahoo's board 5.25 at 9:42; the AP gives a morning low of 5.20. Investrade has a touch of 5.304, "pushing above its 2007 intraday peak of 5.303% to its highest since May 2002." Those round to different hundredths, and the Treasury's Wednesday row had not posted at 9:40 p.m. At the close, the AP says 5.29 and Investrade 5.297, up 4.2 basis points.
Wrong tomorrow
Thursday opens the fourth quarter: jobless claims at 8:30, the ISM manufacturing index at 10:00, a long list of Fed speakers—eight things to expect. The point is not only what arrives, but whether it arrives on time and is measured against the right base.
1. Claims at 7:30 and the ISM at 9:00. Entry 5 will travel. Any calendar or preview carrying those times took them from the same list.
2. "Inflation cooled from 3.7." July is 3.4 now, and 3.0 on the core. A recap or Fed-speaker story with PCE inflation falling three tenths in a month is measuring from a number the BEA has withdrawn.
3. Two factory indexes as one. S&P Global's final September reading (flash 57.0) lands at 9:45 and the ISM's (consensus 54.8, from 54.6) at 10:00. Expect 57 quoted as the ISM, or the ISM's prices index (consensus 72.9) printed as its headline.
4. Claims measured from the wrong line. Consensus is 201,000, from 197,000; the four-week average is 202,250. Expect the average to print at last week's level, as Schwab did a week ago (entry 141).
5. Brent "plunges five dollars." November expired on Wednesday at $103.53, and December settled at $98.03. A board that rolls overnight will show a fall of about $5.50 that did not happen. December against December is the comparison.
6. A fourteenth time. Wednesday's changes (−19.30, −443.87) beside Thursday's contract levels on Trading Economics' page at the open. Level less change should equal 7,670.84 and 51,349.92.
7. September and the quarter, swapped or stale. The S&P 500 lost 0.45 percent in September and gained 2.03 percent in the quarter; the Dow lost 4.29 percent and 2.70 percent; the Nasdaq gained 1.86 percent and 2.47 percent. Expect Kiplinger's 0.2 and 4.0 repeated, or a month's figure given as the quarter's.
8. The ten-year's record, a day stale or a touch too far. "Highest since 2007" is behind the data if Wednesday's 5.304 stands. Expect it anyway, and "closed above 5.30" on the strength of a touch. The Treasury's Wednesday row settles the close.
Thursday night's Errata scores them, as reporting, not as a grade.
Sources and data notes
Every figure carries its feed and the minute it was read, Eastern. Pages reach this desk through a reader that relays their text; quotations on which an entry turns were read twice, except Schwab's headline, read once at 9:48 p.m.
Wednesday's close. S&P 500 7,651.54 (−19.30), Dow 50,906.05 (−443.87), Nasdaq Composite 26,861.06 (+63.52) per the Associated Press, 4:16 p.m., read 9:21 p.m., and the AP's story on BNN Bloomberg, 4:33 p.m.; Kiplinger carries 50,906 and 7,651, read 9:44 and 9:47 p.m. Sworn in for the Dow and the S&P 500. Investrade's review, stamped 4:13 p.m., has 50,908 (−441.13) and 7,652 (−18.81): an early table, a difference, not logged.
PCE. The BEA's release, read 9:48 p.m.: August +0.3 percent, core +0.2; 3.4 and 3.0 over the year. July's revised rates per FXStreet, 8:30 a.m. and Investrade (core only); July's revised monthly 0.1 per TechTimes: Schwab, 9:13 a.m. The consensus of 0.3 and 3.7 per TheStreet's live blog, read 9:21 p.m.; Schwab's note gives 0.4 and calls the annual rate "in line with estimates," a second survey, not logged. CNN's story and CNBC's live page could not be fetched.
Entries 3 to 6. The Motley Fool, 5:03 p.m., read 9:21 and 9:40 p.m. Trading Economics, United States and Japan, read 9:27 and 9:44 p.m. Investing.com's preview, read 9:40 and 9:44 p.m.; Kiplinger's calendar, 9:48 p.m.; Kiplinger, 30 September 2025, 9:44 p.m.; FXStreet, September 2025, 9:22 p.m.; the Conference Board's release.
Oil. Wednesday: WTI for November $90.42 (+1.2 percent); Brent for November $103.53 (+0.9), expired; Brent for December $98.03 (+1.9), per Bloomberg on Rigzone, 4:35 p.m., read 9:47 p.m. Tuesday: $89.38, $102.59 and $96.16 per Rigzone, 9:28 p.m. Investrade's Tuesday preview, mid-morning note and review, read 9:30 and 9:49 p.m.; Kiplinger, 29 September, 9:49 p.m. Investing.com's December table has $97.88 for Wednesday against $98.03 on Rigzone and the AP: a difference, not logged.
Gold. TheStreet, 10:07 p.m. Tuesday, read 9:34 and 9:47 p.m. December's settlement per Investrade's review of 28 September and 24/7 Wall St., 9:28 p.m.
The ten-year. The Treasury's par curve, read 9:34 and 9:40 p.m.: 5.24 Monday, 5.26 Tuesday, no Wednesday row. The AP's Tuesday story on CMG Plus (5.26) and BNN Bloomberg (5.25). Yahoo Finance's boards on its live page (6:00 a.m.) and its copy of TheStreet's blog (9:42 a.m.).
September and the quarter. 31 August closes of 7,686.14, 53,185.90 and 26,370.89 per the AP via Yahoo and Investrade's rounded table; 30 June closes of 7,499.36, 52,319.20 and 26,213.72 per the AP via WTOP, with StatMuse for the Dow alone; the quarter rests on one wire for two indexes. Investrade's figures agree to the tenth, except the S&P's September at 0.4. 24/7 Wall St., Tuesday, 9:47 p.m.; CoinCentral, Monday.
Scoring. The BLS release; FedRateCalc, 9:29 and 9:49 p.m.; Reuters via Yahoo; FXStreet; investingLive; Trading Economics. DPA via Yahoo; Quartz. The Board's calendar, 9:30 and 9:49 p.m.; Cook's speech page; Newsquawk; Reuters via WBOW. All read between 9:22 and 9:36 p.m. unless stamped.
Thursday. Consensus per Investing.com's preview; times per Kiplinger's calendar, with FinanceCalendar's ISM listing seen in search and not opened—speakers per FXStreet, 2:30 p.m.
This desk's arithmetic. September: 7,651.54 ÷ 7,686.14 is −0.45 percent; 50,906.05 ÷ 53,185.90, −4.29; 26,861.06 ÷ 26,370.89, +1.86. The quarter, on the 30 June close: +2.03, −2.70, +2.47. The S&P's month at Tuesday's close: 7,670.84 ÷ 7,686.14, −0.20. Trading Economics: 7,677.36 + 19.30 = 7,696.66. Brent: 105.12 − 96.35 = 8.77; WTI 92.33 − 90.79 = 1.54. Gold: 4,168.40 − 4,135.40 = 33.00.
The Chronicle. 157 at the start of this issue; 167 after tonight's ten additions, numbered 159 to 168.