Morning Brief · Monday, October 26, 2026 · Midday Edition
Monday Brief October 26th 2026
The S-1, the share sale and the surprise: Anthropic files, Meta passes the hat, Brazil votes for Lula
Monday, October 26, 2026 · Morning Brief · Midday, 12:30 p.m. ET · Four figures
The short version
Anthropic filed. The public S-1 hit at 9:00:11am by one time stamp, for a Nasdaq listing as ANT, with Goldman Sachs and Morgan Stanley leading the 22 banks. The audited figures match the draft figures Reuters reported in September: 2025 revenue $4.585bn, operating loss $8.06bn, net loss $41.97bn, of which $34.3bn was a non-cash charge on the convertible notes. The new figures are for the first half of 2026: revenue $16.29bn, an operating loss of $693m, operating profit in Q2, and $131.65bn in cash and short-term investments as at June 30. There is no price range, no third-quarter number and no $518bn. There is $265.6bn in non-cancellable purchase commitments and $321.4bn in undiscounted leases (with Broadcom, Google, Amazon, Microsoft and SpaceX all named).
Meta is raising $95bn. A free-writing prospectus this morning: $35bn underwritten. It will sell $22.5bn of Class A shares via forward sale agreements and $12.5bn of depositary shares in a mandatory convertible preferred, which will convert in August 2029. The company also has an at-the-market program for the new Class C stock of up to $60bn, which is "not expected to commence until the first quarter of 2027". Nvidia, AMD and Broadcom are the named cornerstone investors with a non-binding indication to buy up to $5bn. Proceeds are for general corporate purposes. The stock was down 1.8% at 10:01 and flat at 12:16.
Brazil has broken. Lula won the run-off on Sunday, 51.79 to 48.21, over Flávio Bolsonaro (now seeking annulment), by 4.4 million votes. The Bovespa dropped 17% to 169,516 by 10:57 with a 30 minute halt; the real down over 12% to R$5.61; the Treasury cancelled this week's auctions; EWZ down 25% and on track for its worst day ever; XP down 50% at 10:22, Nu 20, MercadoLibre 10, Petrobras about 21; Itaú, Bradesco, StoneCo and PagSeguro down 27 to 37% in the premarket. The market had been positioned for the other result, with $4.09bn flowing into EWZ between 1st and 23rd October.
Week is Wed/Thu. Fed decision at 2 pm Wednesday (hold at ~90%), Warsh at 2.30. Alphabet at 4.30, Microsoft at 5.30 that same afternoon. Thursday: Q3 GDP (3.0 to 3.2% expected), Sep PCE (3.6% headline, 3.1% core) at 8.30, ECB and Amazon and Intel after the close. Apple is not this week (it's Monday 2nd Nov). Midterms are Tuesday 3rd.
The tape since the open
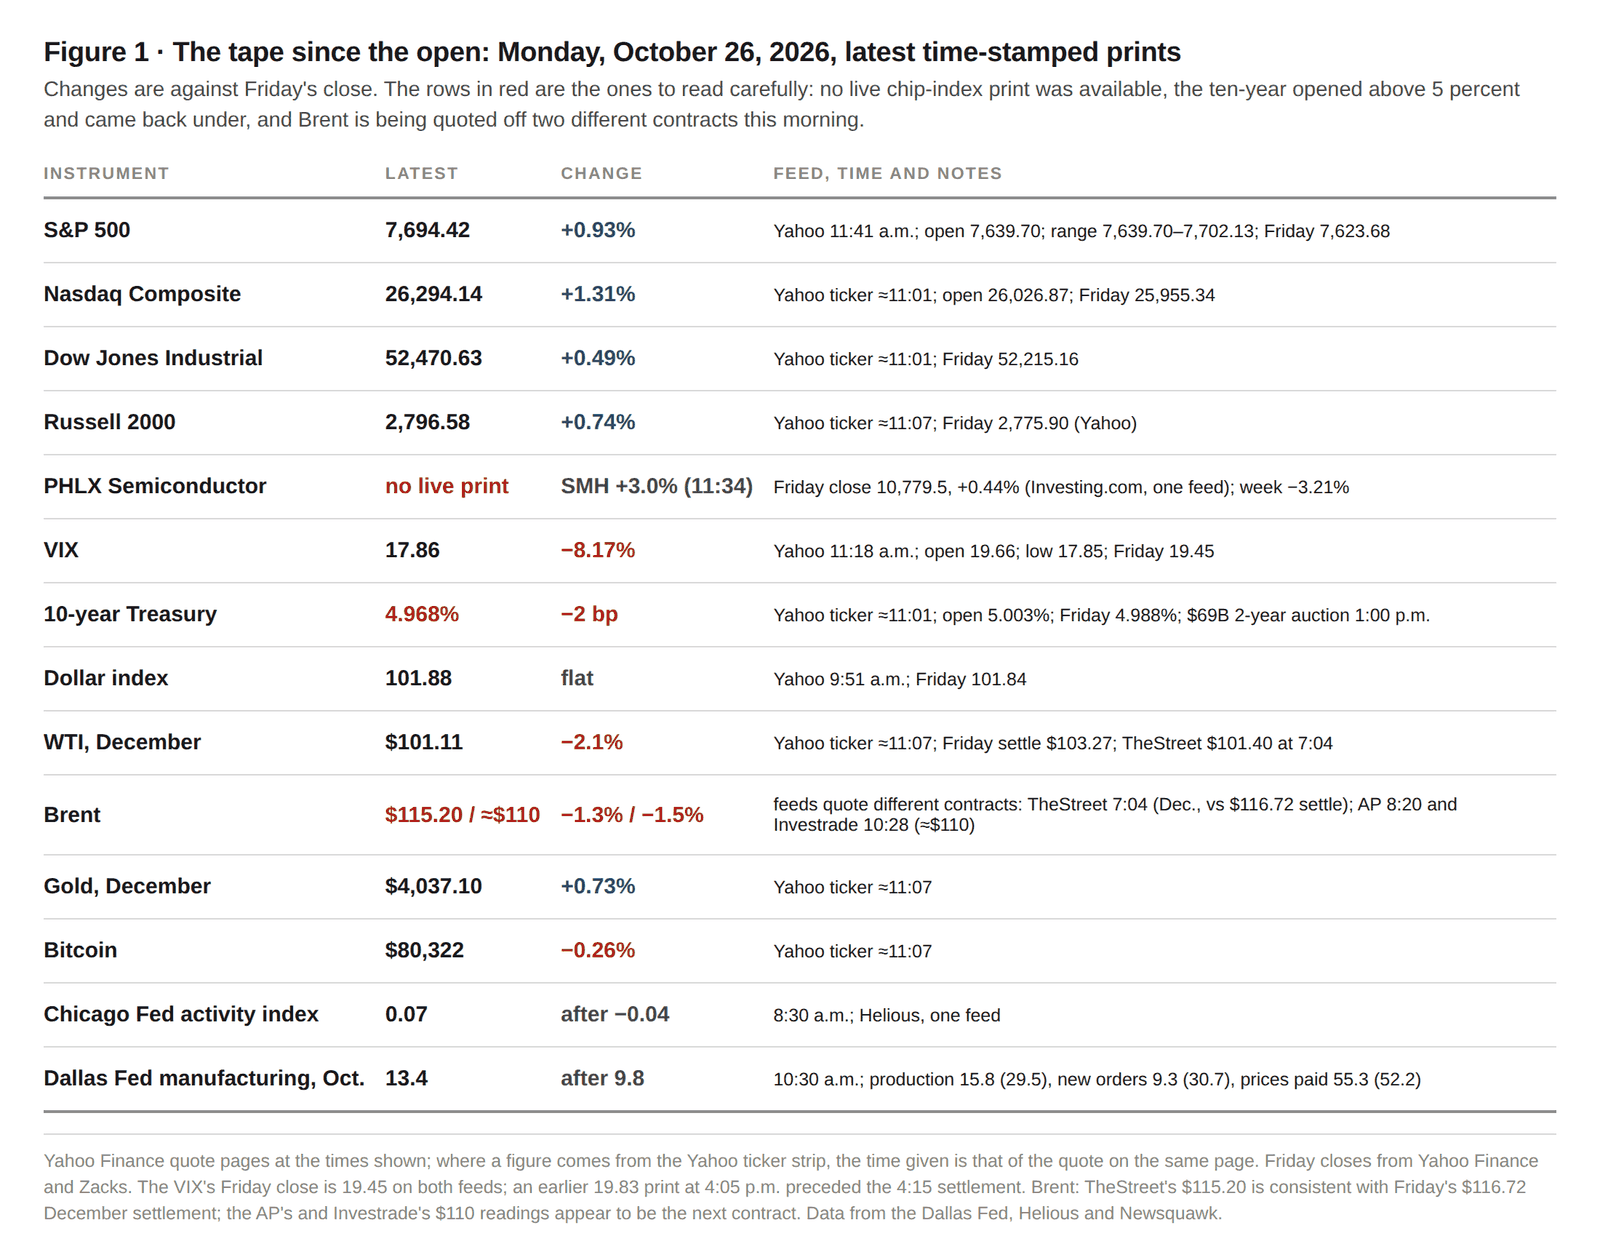
The open was unremarkable, and the first hour was not. Reuters had the Dow up 105 at the bell, the S&P up 16 and the Nasdaq up 71. TheStreet had the S&P up 0.97% at 10:53 and stocks "up and oil sliding" at 11:22. The VIX opened at 19.66 and printed 17.85 at its low (a one-session collapse of the hedge put on into Friday's $103 oil close). Rates are helping: the 10-year opened at 5.003% and was 4.968% at 11:01. The Treasury sells $69bn of 2-year notes at 1:00 this afternoon, $70bn of 5-year notes tomorrow, and $44bn of 7-year notes Thursday. The dollar index is 101.88, flat.
Oil is the other relief this morning. Dec WTI was $101.11 at 11:07 (down 2.1% on Friday's $103.27 settlement) on the mediation reports (TradingKey have Qatari mediators in Tehran working with Washington; AP have delegations from Saudi Arabia, Pakistan and Turkey, which are both printed as they don't agree). Brent is a contract issue this morning, so we flag it so you don't misread it. TheStreet is at $115.20 at 7:04 (down 1.3% from Friday's $116.72 settlement), while the AP and Investrade are at about $110 (down 1.5%) on what appears to be the next contract. CNN reported overnight that U.S. forces could launch major operations against Iran "within 96 hours of receiving" an order and that it is "when, not if", with most officials expecting the order to come after the midterms (which is why the relief is only 2%). Dec gold is $4,037 (up 0.7%) after last week's 4% fall. Bitcoin is $80,322 (down 0.3%).
The data was a footnote really: the Chicago Fed's NAI was at 0.07 (up from -0.04), the Dallas Fed's October manufacturing index was up to 13.4 (from 9.8) with production down to 15.8 (from 29.5), new orders down to 9.3 (from 30.7) and prices paid up to 55.3. That's a survey where sentiment improved while the order book actually weakened and prices rose. That's the whole economy in one table.
Anthropic's prospectus, read against the draft
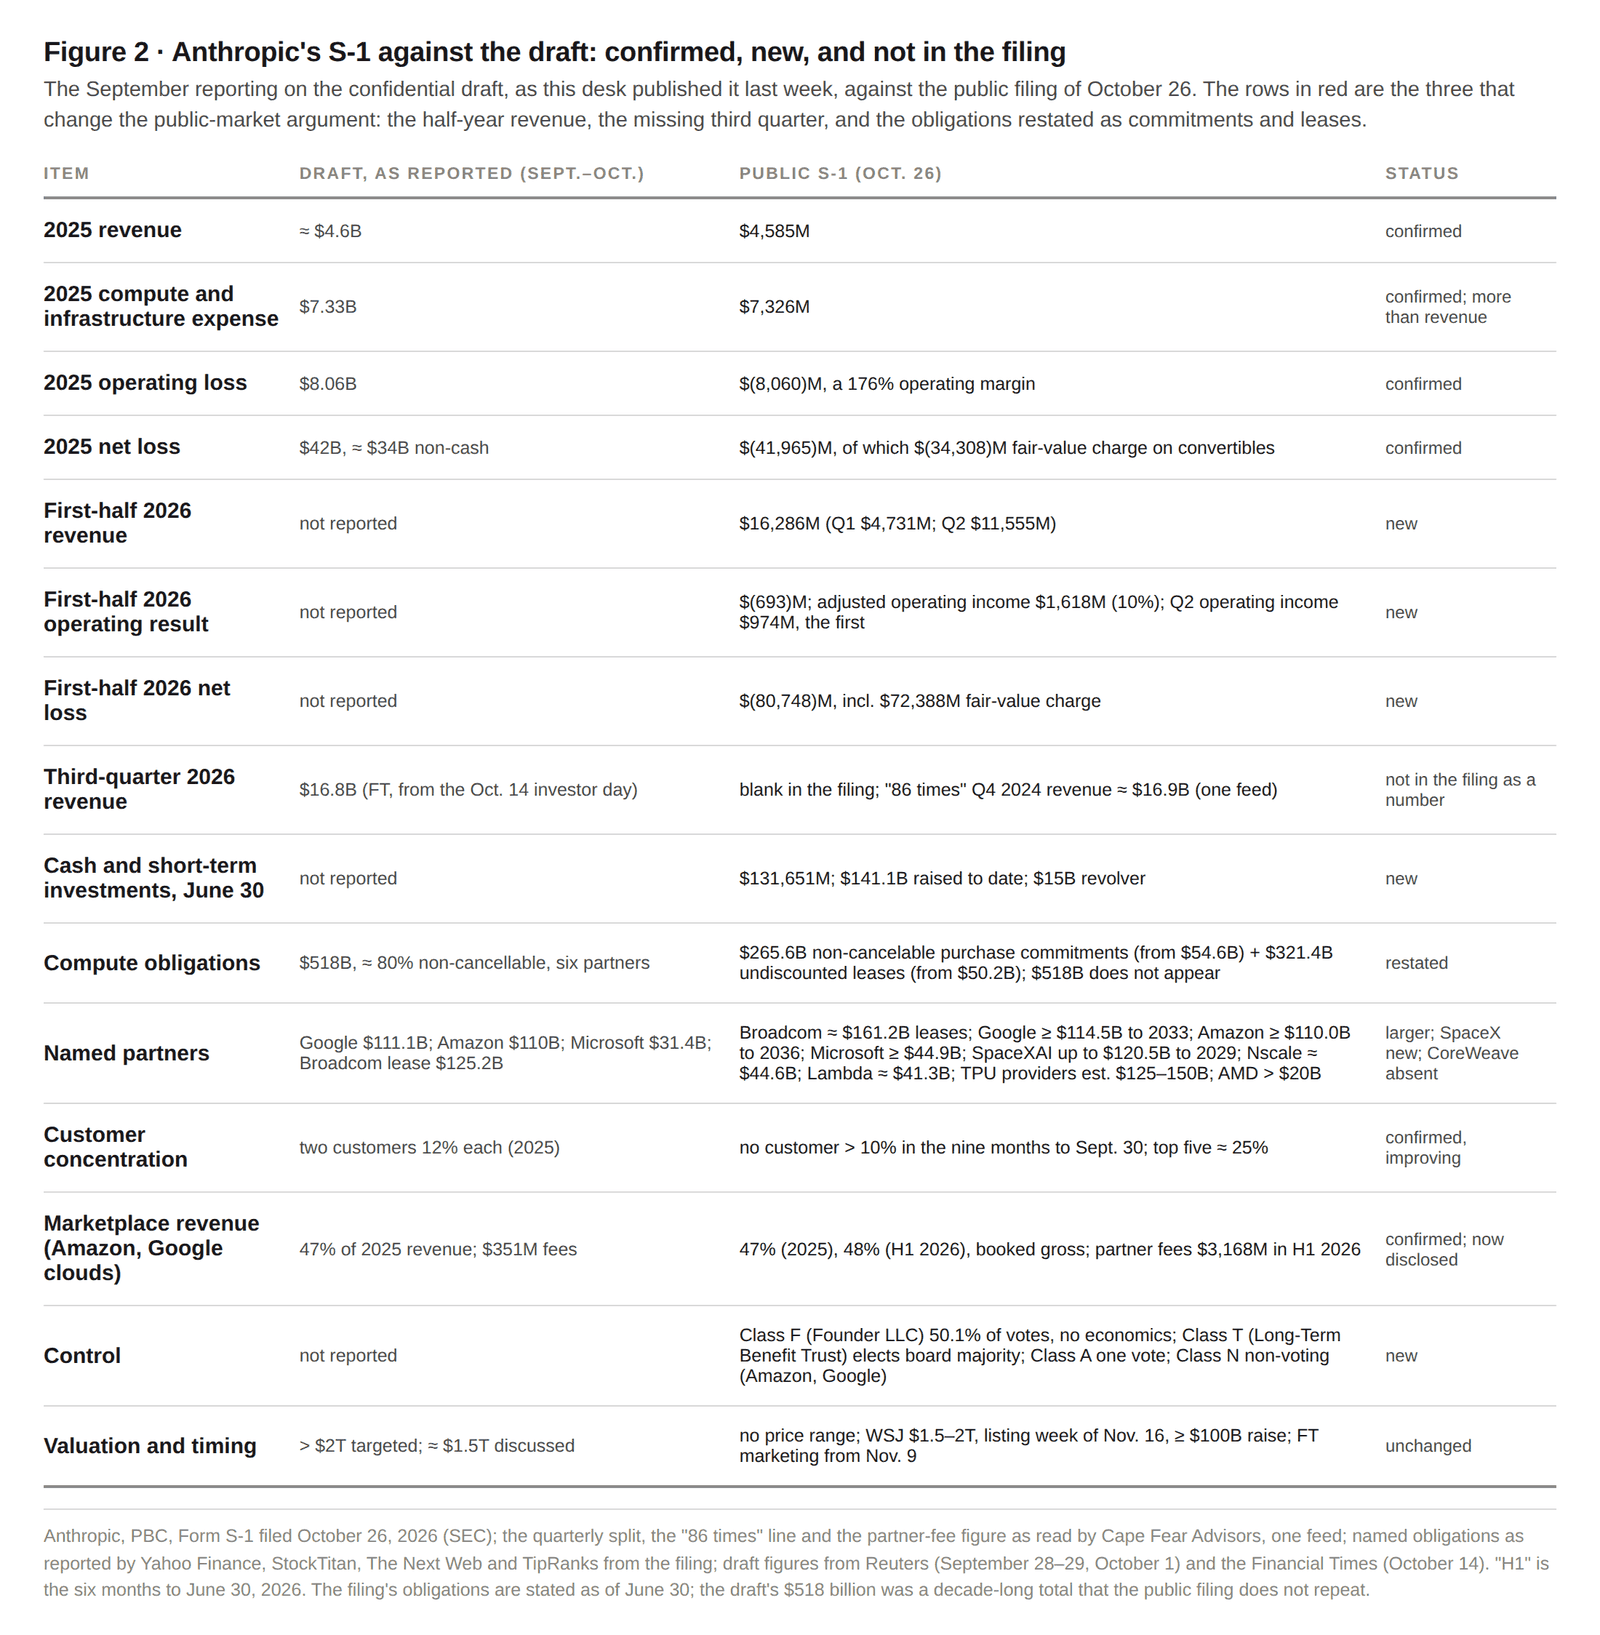
The S-1 confirmed the September reporting to the penny. 2025 revenue was $4.585bn; cost of compute and infrastructure was $7.326bn (more than revenue); operating loss was $8.06bn (176% operating margin), and net loss was $41.965bn, of which $34.308bn was the change in fair value of the convertibles, derivatives and SAFEs. 2026 is the new story. H1 revenue was $16.286bn (up from $1.16bn in H1 2025: $4.731bn in Q1 and $11.555bn in Q2 per one feed's reading of the quarterly table). H1 operating loss was $693m; adjusted operating income was $1.618bn (10% margin); Q2 operating income of $974m was the first quarterly operating profit. H1 net loss was $80.748bn, almost all of which ($72.388bn) was the fair value charge on the convertibles (the accounting impact of the company's value increasing between financing rounds). That will stop mattering on the day the notes convert.
Q3 is not listed as a number in the filing. The risk factors have it blank; the business section (one feed) has it at "86 times" the revenue of Q4 2024, which on a $197m base is approximately $16.9bn (again consistent with the $16.8bn the FT reported at the Oct 14 investor meeting). Cash and short-term investments were $131.651bn as at June 30th, on $141.1bn raised to date, with a $15bn revolver in place since September. No customer accounted for more than 10% of revenue in the nine months to September; the top 5 were around 25%; in 2025, two customers were 12% each. Marketplace sales via Amazon and Google Cloud were 47% of 2025 revenue and 48% of the first half (booked gross), with partner fees at $3.168bn in the first half versus $120m a year earlier, all included in sales and marketing. That is the disclosure OpenAI has complained about, and it is now on the record in Anthropic's own words: the company "is the principal and recognizes revenue on a gross basis".
The public market will look at the obligations first, and the $518bn figure from the draft isn't in the filing. It has non-cancelable purchase commitments of $265.6bn as at 30 June (up from $54.6bn at the end of 2025) and undiscounted lease obligations of $321.4bn (up from $50.2bn). The named counterparties as reported from the filing are: c. $161.2bn of rent on 5 year equipment leases to Broadcom; at least $114.5bn to Google through 2033; at least $110.0bn to Amazon through 2036; at least $44.9bn to Microsoft from Nov 2026 to May 2033; up to $120.5bn to SpaceXAI for Nvidia GPUs through 2029 (cancelable on 90 days' notice after early 2027); up to $44.6bn to Nscale and $41.3bn to Lambda; an estimated $125-150bn to TPU providers (including Google); and over $20bn to AMD. The outlets' own figures range from $430.6bn for the four non-cancelable deals to around $637bn for all named deals, and the WSJ's up to $750bn, including deals still under discussion. CoreWeave doesn't appear as a supplier. SpaceX appears as a compute seller with a $120.5bn ceiling, the first time that number has appeared in the market.
The structure is the other thing to know. Class A shares carry one vote and are the shares that list. Class N is non-voting and is what Amazon and Google will own. Both will own more than 5% post-IPO. Amazon has invested $18.0bn since 2023, of which $6.2bn is in notes that convert at the IPO (subject to a 12% cap). Google has invested about $20.0bn in preferred stock this year and has a right to buy up to $10bn more of Class N at the IPO price. The Long Term Benefit Trust holds Class T and elects a majority of the board. The Founder LLC holds Class F, carries 50.1% of the voting power, and has no economic rights or dilution on new issuance. The lock-up is staged with non-founder insiders free to sell up to 10% on day one and the co-founders 29% at the earlier of Q1 results or day 180. The Journal has the listing targeted for the week of 16th November, with terms in about two weeks and a raise of $100bn or more. There is no price range. The Journal's valuation range is $1.5 to $2trn. Reuters' investor day range is $1.5trn. The FT's is $1.8 to $2trn. Matt Kennedy at Renaissance Capital to Reuters: "Not even Anthropic will get a blank check." LightShed's line via CBS is the one that will be quoted all month: "Anthropic could become the most valuable company in the world. It could also end up in bankruptcy."
The stocks that get paid are the trade (as the desk noted last Tuesday), and they were all bought at the open: Broadcom up 2.55 at 12.17, Amazon up 0.18 at 12.13, Microsoft up 1.04 at 12.07, Alphabet down 0.61 at 9.58 on its last print. The filing mentions Nvidia only as a supplier, not as an investor, and it was up 2.16 at 12.16.
Meta passes the hat
The other document is Meta's raise. That's what Thursday's selloff was all about. The free writing prospectus details approximately $35bn of underwritten offerings: $22.5bn of Class A common to be sold via forward sale agreements with Morgan Stanley and Goldman Sachs as forward purchasers, with settlement on or before 19th November 2027, and 250m depositary shares (each being 1/20th of a Series A mandatory convertible preferred share) for about $12.5bn, converting on or about 15th August 2029 with the dividend rate and conversion terms to be determined at pricing. The underwriters have options on an additional 37.5m depositary shares and $3.375bn of Class A. The at-the-market program for the Class C shares (the non-voting class created by the charter amendment filed 21st October and described to shareholders as a 2-for-1 split) is up to $60bn and doesn't start until next year. Nvidia, AMD and Broadcom are the "Cornerstone Investors" who "have, severally and not jointly, indicated an interest in purchasing up to an aggregate of $5.0 billion" of the Class A; that interest is non-binding.
Read the three names together, and you see the circle described in the Anthropic filing with Broadcom. The companies that sell Meta the chips are offering to buy the shares Meta is selling to pay for the chips. That same circle is now on Meta's cap table. William Blair's note this morning is the obvious one: "We expect investors to continue to question the financing and potential for future capital raises." The stock was at $631.14 at 10:01 (down 1.79%), and at $642.17 at 12:16 (up 7 cents), so the market clearly sold the headline and bought the fact that the money had been raised.
The AI complex since the open, and the post that started the day
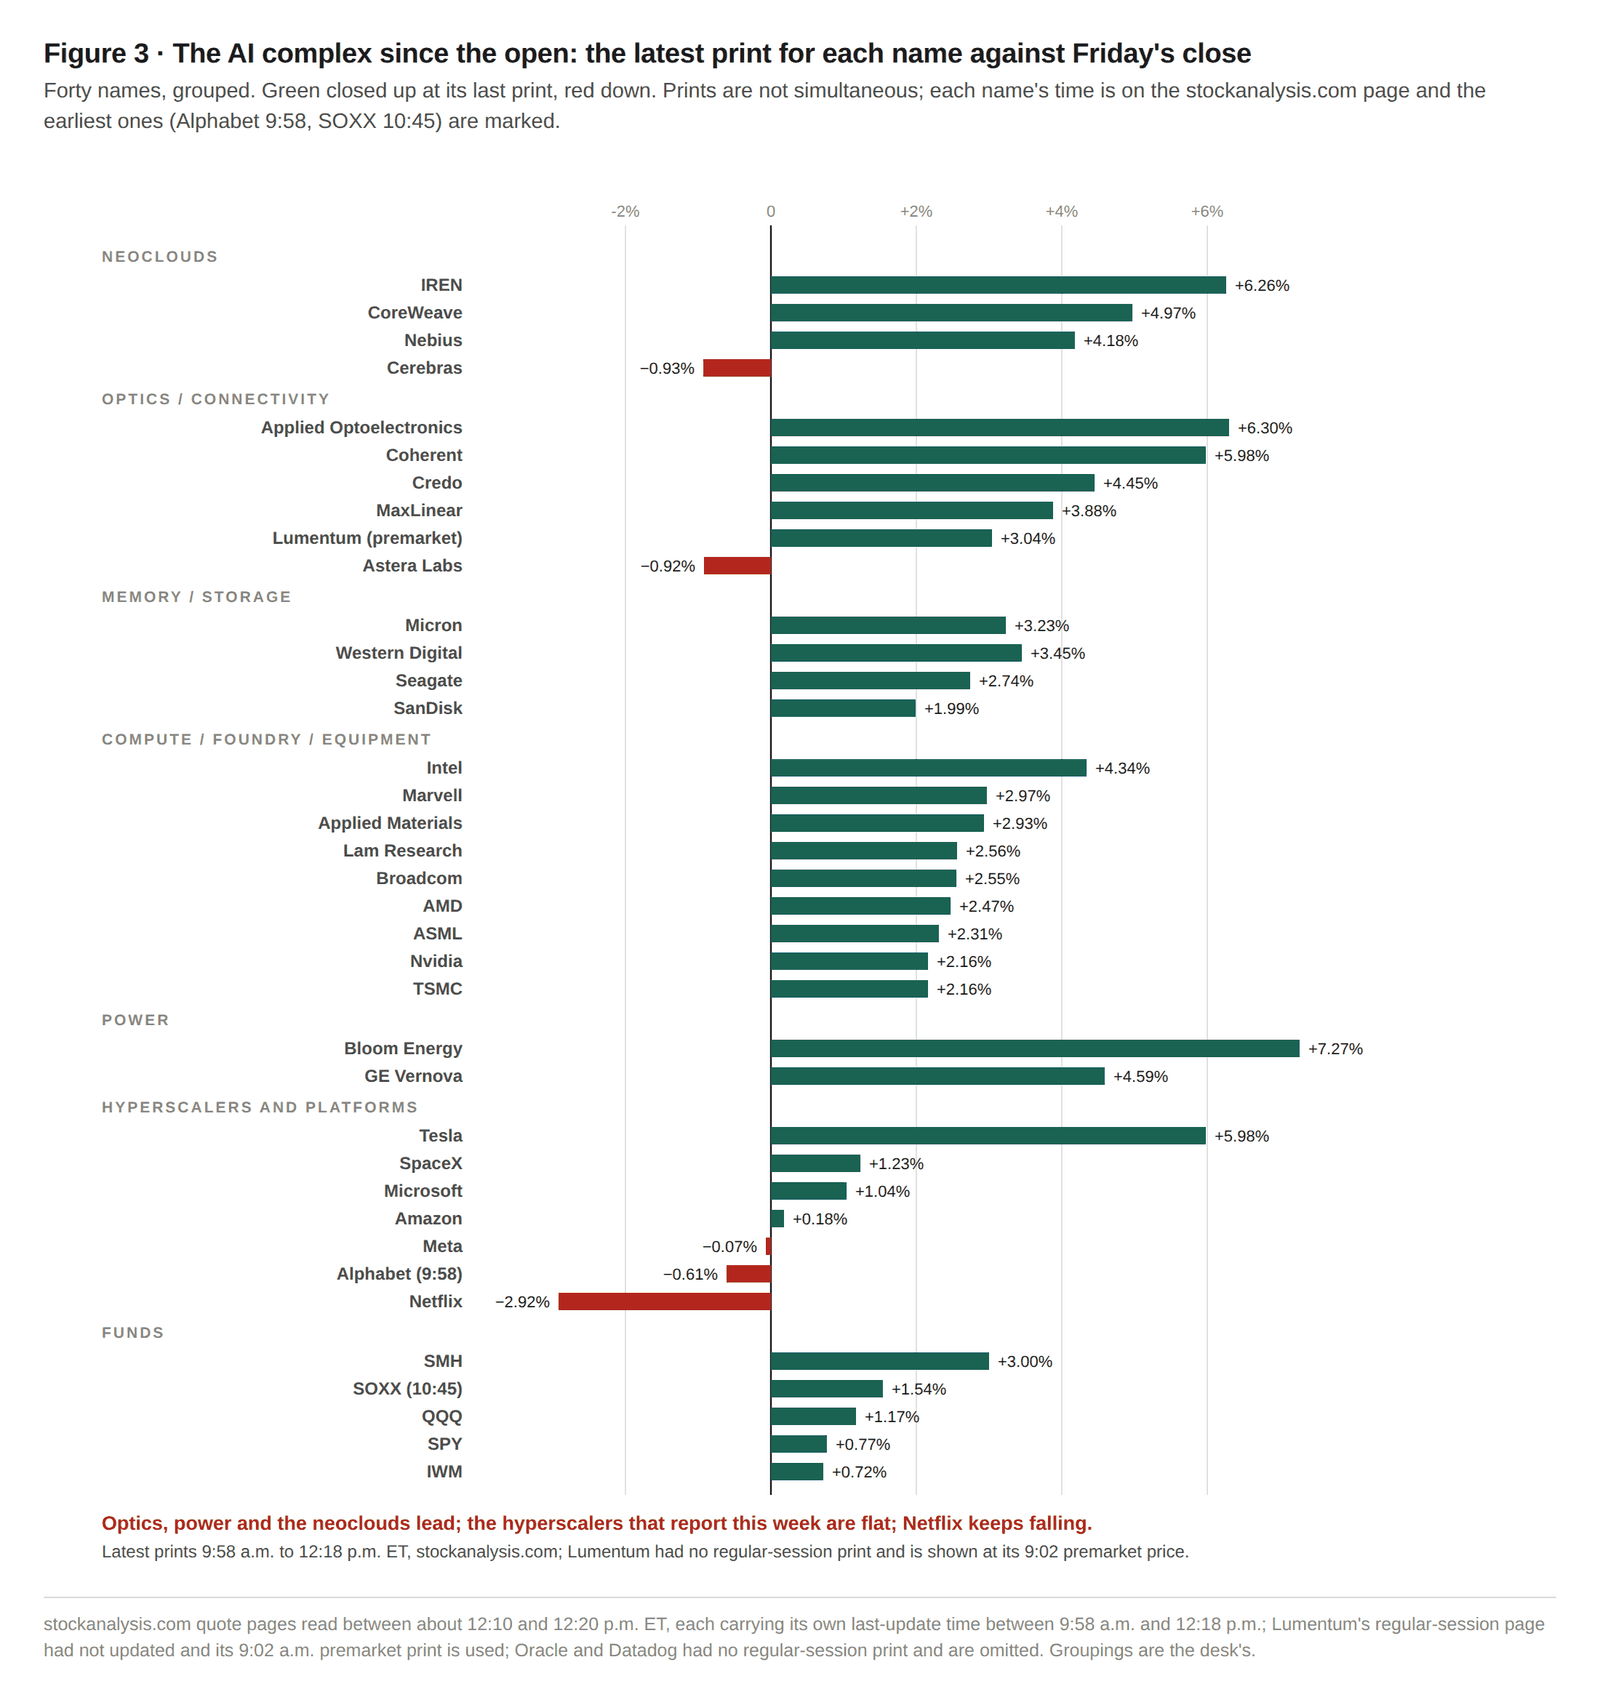
Elon Musk posted on X on Sunday that "the 200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many." This came a day after he'd written that "we're going to see a lot of stranded compute in partially complete data centers", and he added that SpaceX would not buy any of them (calling the idea "pointless"). CoreWeave was down 2.7% and Nebius 3.5% in the 5 am premarket on that. By mid-morning, both had reversed: CoreWeave $56.93 at 11:51 (+4.97%), Nebius $165.37 at 11:39 (+4.18%) and IREN $26.47 (+6.26%). A filing supports the reversal. In the Anthropic filing, we see Nscale at up to $44.6bn and Lambda at $41.3bn ($86bn of contracted demand for two private neoclouds), and the public market, which had spent a week trying to sell the story that no one would sign any long-term contracts with them, read the filing and covered. Cerebras (-0.93% at 12:06) and Astera Labs (-0.92%) were the exceptions.
The same post details SpaceX's financing. Musk says they have $40bn of "primarily callable debt for GPU purchases that will arrive in Q1 and Q2" and that SpaceX is "investment grade". Bloomberg's version is a bit more detailed and less polished: it's an off-balance-sheet vehicle to finance the Nvidia GPUs, structured by Goldman Sachs with investors led by Apollo (an Apollo-backed Atlas SP managing the vehicle), PIMCO were considering getting in, there are Rule 144A placements, and the pricing discussions have been caught up in the neocloud mess, so it's not at all clear what "closed" means or whether a price has actually been agreed. CFO Bret Johnsen: "We have a lot of conviction that we are going to be able to do this in a very measured fashion." SpaceX was at $149.31 at 12:08 (up 1.23%), Tesla was at $394.47 at 12:15 (up 5.98%) following Barclays' Dan Levy upgrading the stock to Overweight with a $450 target from $370 on the merger: "With a combination heavily expected, and with expectation for some premium to TSLA stock," an all-stock deal with SpaceX as the acquirer that would require more than half the voting power of each company (a "high hurdle", per Barclays, who estimate that leaves Musk with around 53% of the combined votes).
Elsewhere across the complex at the latest prints: AMD $529.58 (+2.47), Broadcom $329.88 (+2.55), Marvell $235.30 (+2.97), TSMC $427.57 (+2.16), ASML $1,608.14 (+2.31), Lam $236.00 (+2.56) following its 11.8% drop on Thursday, Applied Materials $388.30 (+2.93), Intel $90.74 (+4.34) three days before it reports. Opticals led: Applied Optoelectronics +6.30, Coherent +5.98, Credo +4.45, Lumentum +3.04 in premarket, and MaxLinear +3.88. Storage held its own: Western Digital +3.45, Seagate +2.74, SanDisk +1.99. Power was the big winner: Bloom Energy +7.27, GE Vernova +4.59. Netflix down another 2.92% at $63.93.
Brazil, and why it matters here
The numbers are in the short version; the reasoning is what to take away. The market had priced in a Bolsonaro win, and the selling is, first and foremost, the unwinding of that position. Goldman's Alberto Ramos and Panteleymon Semka have this morning written that major reforms are now unlikely, that they expect modest spending controls, higher taxes and state companies as growth drivers and that "fiscal sustainability remains the primary pricing anchor for Brazilian sovereign risk". Public debt is above 82% of GDP, and Lula's own target is a primary surplus of around 1.3% of GDP by 2030. Sector-specific fears include tax increases and tighter regulation for banks and fintechs, which is why Nu, XP, Itaú, Bradesco, StoneCo, and PagSeguro all fell 20-50%, and state intervention, fuel price controls and dividend risk at Petrobras, down around 21%. No one is talking about capital controls. Brazil's dollar bonds were the worst performers in emerging markets this morning, with the 2056 bond down nearly 3 cents and the Treasury cancelling both the inflation-linked and fixed-rate auctions on Tuesday and Thursday, respectively.
For an American desk, the question is contagion, and the answer to date is none. The S&P is up a percent, the dollar index is flat, and the selling is all in Brazilian paper and the ETFs that hold it. That's something to watch, not assume. The $4bn of EWZ inflows in October came from somewhere, and a 25% one-day loss in a crowded position will trigger selling elsewhere by Wednesday.
The rest of the tape
EQT is buying Range Resources in an all-stock deal at 0.987 EQT shares per Range share (approx. $54.91, 20.6% premium to Friday's price) for an equity value of $12.8bn (Reuters) or $14.05bn (other source) with a combined company enterprise value in excess of $50bn. The deal will create a company with over 9 billion cfe/day of production and $325m of synergies, which will grow to over $600m. The announcement mentions Appalachian demand, LNG and liquids; Reuters adds data centre power and the EIA's forecast of domestic gas use rising to 94.3 bcf/d by 2027 from 91.9 bcf/d. Range is up 15.95% at 10:22; EQT is down 3.3% in the premarket on the dilution, as is typical of an all-stock deal. Close is expected in Q1.
Verizon did well where it counts, and the stock still went down: 406k postpaid phones added vs 209k estimated, adjusted earnings of $1.31 vs $1.27, the 2026 subscriber guide raised to 1.1-1.2m (was 750k to 1m), and a fibre deal with AWS worth over $2bn for AWS data centre connectivity. Revenue came in at $34.3bn (missed $34.74bn), and the stock was down c. 2.5% on one feed. AT&T and T-Mobile were down 7.96% and 7.71%, respectively, on Friday after a Bloomberg report said SpaceX is in talks to access about 80k cell sites (enabling it to build a 4th national network), and we had no fresh prints to time. Fair Isaac was down 8.6% after maintaining its mortgage score at $10 for lenders who would use it exclusively, which Wells Fargo's Jason Haas read as a cap on earnings upside, downgrading to Equal Weight with a $735 target. JPMorgan cut its target to $900 from $1,530. Comfort Systems up 6.8% on the quarter, Reddit down 4.7% ahead of Thursday's report, Nutanix up 5 on a Guggenheim initiation and Moderna down 7 on its cancer vaccine data.
Europe went the other way. Moody's held France at Aa3 with a negative outlook on Friday night, based on the assumption (as they put it) that "a deficit-reducing budget for 2027 will be adopted", and the market took that non-downgrade as the news: the OAT-Bund spread narrowed to around 161bps from 176, the CAC 40 up 0.8% to 7,840.87, BNP, Crédit Agricole and Société Générale all up 1 to 1.6%, DAX up 0.8% to 25,389.86. The FTSE 100 is down 0.5% on the AP's read and up 0.4% on the other; both are printed. The Interior Ministry said Saturday's protests totalled 410k, while the CGT said about 800k, with 1,314 arrests versus 2,628 the previous Saturday; the unions have called for marches next Saturday and a national strike on 5th November. Asia was down ahead of their own chip earnings: Nikkei down 0.8% to 62,189.60, KOSPI down 1.46% to 5,469.47 on foreign selling, Samsung down 1.16%, SK hynix flat (SK hynix reports on Wednesday, Samsung on Thursday Korea time). Taiwan was closed on Friday for the typhoon and a holiday and will reopen on Tuesday. China's 5th Plenum runs through to Thursday.
The week, and what to watch
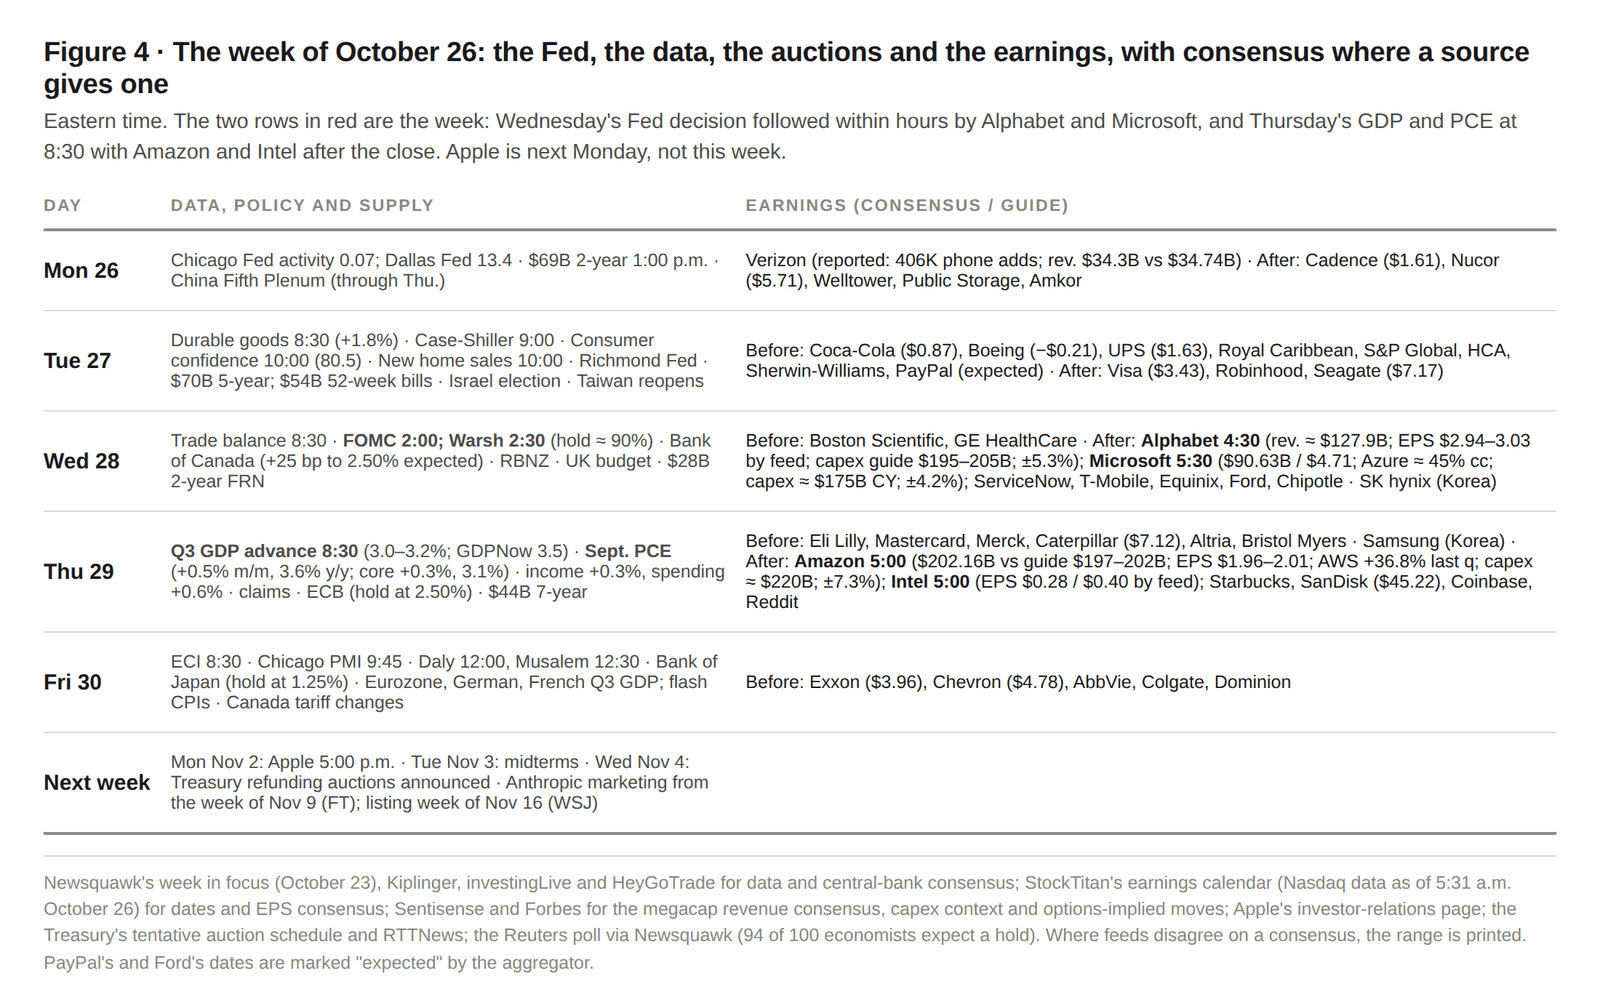
Wednesday has three events in four hours. FOMC statement at 2:00 (hold at about 90% with Warsh at 2:30); Alphabet at 4:30 (consensus around $127.9bn revenue and $2.94 to $3.03 earnings across feeds, 2026 capex guide already at $195 to $205bn and Cloud up 82% last quarter); Microsoft at 5:30 (consensus of $90.63bn and $4.71, Azure guided to around 45% in constant currency, capex around $175bn for the year with over $50bn in the September quarter). The options imply 5.3% for Alphabet and 4.2% for Microsoft. My view is that the Fed holds, and the press conference is the risk. A chair asked about $110 oil and a 0.6% CPI can't sound relaxed, and the long end that rallied last week on fear will be a bit re-priced if he comes across as unbothered. Bloomberg has Bank of America's Aditya Bhave calling for a surprise hike, and Santander's Stephen Stanley saying, "I expect no change — I do think that they'll hike again in December", with a dissent or two for a hike possible from the three who dissented in July. Then two capex numbers. After Meta, the market will punish capital expenditure without attached cash flow, and both companies know that. Expect both to hold or raise and to be judged on Cloud and Azure growth and free cash flow rather than the capex line. Alphabet has the tougher job as Netflix's ad miss is a week old and Alphabet's ad print is the first big one since.
Thursday is the data and the one hyperscaler that can turn the tape. GDP at 8.30, 3.0 to 3.2% expected (after 2.2) with GDPNow at 3.5%; September PCE at 0.5% headline and 3.6 YoY, core 0.3 and 3.1 (a hot print by any Fed standard and will land the morning after the decision); claims; the ECB expected to hold at 2.50 with Danske calling for a move to 2.75 in December. Then Amazon at 5.00, consensus $202bn revenue (against a $197 to $202bn guide) and $1.96 to $2.01 earnings, AWS up 36.8% last quarter, cash capex near $220bn for the year with the options implying 7.3%. Amazon is the one that can put a cash-generating cloud business alongside its capex line, and the S-1 states Anthropic owes it at least $110bn through 2036, and that Amazon has $18bn in the stock. The print will determine whether the week's AI tape ends up or down. Intel reports the same hour with consensus at 28c on one feed and 40c on the other (a difference worth noting before the headline comes in).
The neoclouds are now a two-tier market, and the S-1 drew the line. Nscale and Lambda have $86bn of named Anthropic demand, CoreWeave has none in this document and a bond yielding close to 15%, Nebius has Microsoft and Meta. The 4-6% bounce today is short covering on the filing, not a verdict on Musk's "guppy-level" line, which is a very accurate description of 190 of the 200. Watch whether CoreWeave can hold today's gain through Wednesday's close (it closed at $54.23 on Friday, down from $61.12 last Monday), and watch the SpaceX vehicle's pricing; it will tell you what the market now charges for GPU-backed debt.
Brazil is the wildcard of the week. The Bovespa has halted, the real is at 5.61, the Treasury auctions have been called off, and EWZ is on its worst day ever. The questions for Tuesday are: will the central bank intervene? Who does Lula name at Finance (which Goldman says is the first thing to watch)? Will the unwinding of the position spill over to other emerging markets? Watch the peso and EEM on Tuesday morning. If they're flat, then this remains a Brazilian story.
Oil and the calendar. 2% of relief on the mediation reports, against a CNN report that the strike option is "when, not if", and is very likely to come after the 3rd of November. Trump himself on October 8 said the U.S. "will not be attacking Iran at any time prior to the Midterm Elections". The market is pricing in the week after. The first Russian diesel tanker arrives in New York on November 7. Don't misread Brent on Wednesday. The December contract (settled at $116.72) and the next one (at about $110) are both being quoted as Brent this week.
Levels. S&P at 7,694 is below its 50-day average (7,706 last week) for a second session. A close above that with the Fed behind us would be the first technical positive since Oct 13. The chip index at 10,779.5 held its 200-day average (about 10,600) through last week's worst day. SMH is up 3% this morning as the group tries to build some distance before Wednesday evening. Micron at $909.79 has the Taichung agreement signed, and the Taoyuan issue (which led to a one-day strike announced last Thursday) is still open.
Bottom line
The three docs of the morning all say the same thing from three different angles. Anthropic's prospectus paints a clear picture of an AI lab with $16bn in half-year revenue, $132bn in cash, and over half a trillion in landlord promises. Meta's prospectus is a hyperscaler asking its shareholders and chip suppliers for $95bn to keep building. Brazil's election is a good example of what a very crowded position looks like when the vote goes the other way. The tape is up a percent on the first two and completely ignoring the third, which is fine on a Monday and will be under pressure on Wednesday when the Fed speaks at 2.00 and then Alphabet and Microsoft put their capex numbers alongside their cloud numbers before dinner. Own the companies that are getting paid to build it. The filing just listed them.
TrendyVest provides market research and commentary for informational purposes only. Not investment advice.