The Closing Edge
The Closing Edge #32
The divergence last week only warned about arrived in full on Monday. A firm services read and relentless Treasury supply drove the ten-year to a fresh twenty-four-year high — and the Nasdaq and Nvidia closed at records anyway. Equities are buying the growth; the long bond is selling the financing of it.
Monday, October 5, 2026 · 4:00 p.m. ET · No. 32 · The daily close
10-yr 5.32% +4 bp · 30-yr 5.67% +5 bp · 2-yr 4.83% (flat) · WTI $89.36 −1.9% · Gold $4,138 · BTC ~$86,000 · VIX 15.5
The close
The split held, and widened. September ISM services printed a firm 54.9 — expansion, not the cooling the doves wanted — and that, layered on heavy government borrowing and a market that still can't find buyers for the long bond, pushed the ten-year Treasury yield to roughly 5.32 percent, a fresh twenty-four-year high, and the thirty-year to a new high near 5.67 percent. The two-year, anchored by a Fed that just hiked, sat flat at 4.83. On any ordinary tape, long yields at a quarter-century high would be an equity problem. This was not an ordinary tape: the Nasdaq rose 1.05 percent to a record, Nvidia added 2.2 percent to a record of its own, and the S&P closed up 0.66. The Dow, most exposed to the rate story, managed only 0.14 percent — the breadth tell hiding inside a green day.
The tape
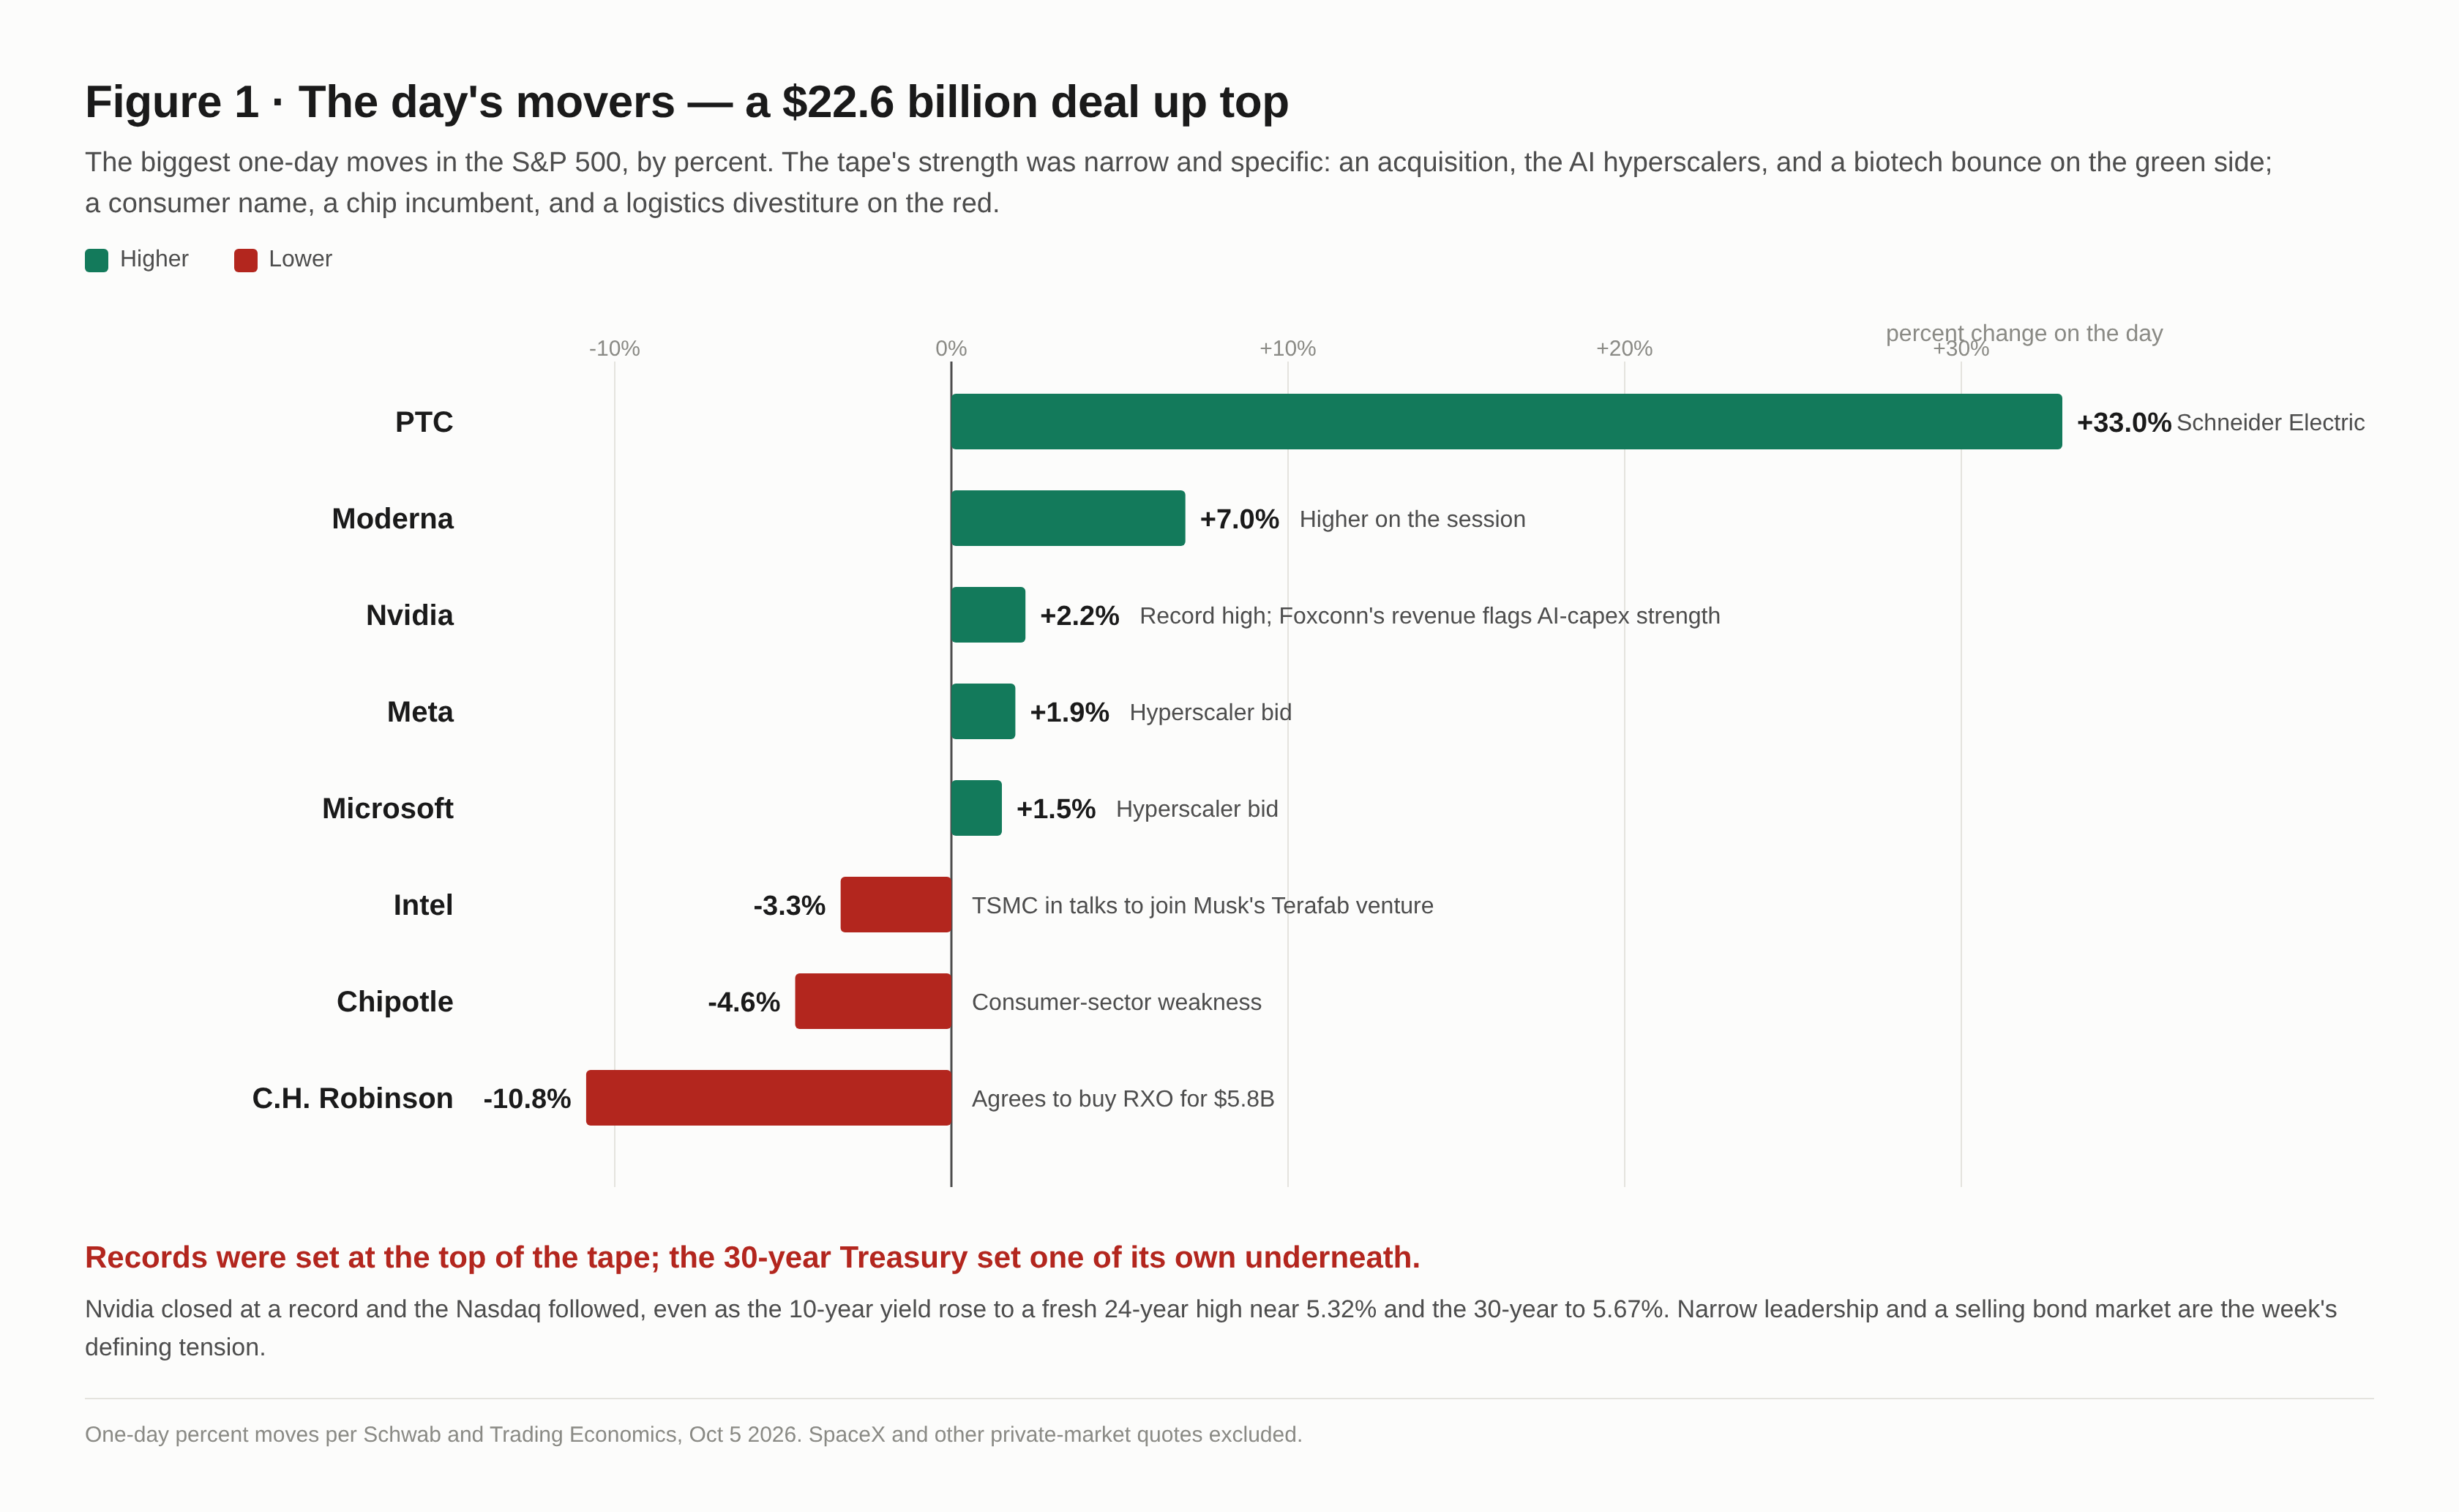
Narrow and specific. The green was concentrated. PTC jumped 33 percent after Schneider Electric agreed to acquire it for $22.6 billion, the day's one clean M&A story. The AI hyperscalers did the index's heavy lifting — Meta up 1.9, Microsoft up 1.5, Nvidia leading — helped along by Foxconn, whose stronger-than-expected revenue read as another signal that the capital pouring into AI infrastructure is not slowing. Moderna bounced near 7 percent. The red was just as specific: C.H. Robinson fell 10.9 percent after agreeing to buy the truck broker RXO for $5.8 billion in cash and stock, an expansion investors judged a stretch; Chipotle slid 4.6 on continued consumer softness; and Intel dropped 3.3 after Elon Musk said TSMC was in talks to join his Terafab chip venture — a setback for the incumbent's foundry comeback.
Across assets. Crude went the other way from the week's geopolitics: WTI fell 1.9 percent to $89.36 after major OPEC+ members agreed over the weekend to hold production quotas unchanged, letting some of the Middle East risk premium bleed off. Gold eased to about $4,138, and Bitcoin climbed back above $86,000 as the odds of another rate hike stayed low. Volatility never stirred — the VIX closed near 15.5, a market entirely comfortable owning record-high equities against record-high yields.
The tell
Two markets, two stories. Equities are pricing the thing Friday's jobs miss handed them: a Fed that is probably done, growth that is holding, and an AI capital-spending cycle still accelerating. The long bond is pricing something equities are ignoring — the supply and term premium of financing a large deficit at a moment when the natural buyer has stepped back. Those can coexist for a while; they cannot coexist forever. Note the repricing even here: the odds of an October hike, which the payrolls miss had driven to roughly 14 percent, firmed back toward the low-20s as ISM held and yields climbed. The hike scare is not fully gone, and the yield problem is getting louder.
Tomorrow
The setup. Tuesday brings the August trade balance and a full slate of Fed speakers, but the number that matters most to the bond market is the three-year note auction — the first of the week's supply tests, and a live read on whether buyers are finally showing up at these yields. The centerpiece is Wednesday's minutes from the September meeting, where the Fed hiked 25 basis points; the value is in how close another move was and how divided the committee is, now read against a labor market that has since weakened. University of Michigan sentiment closes the week Friday. Earnings stay light and pre-bank — PepsiCo and Delta later this week — before the mega-bank kickoff the week of October 13, with the next policy decision the October 27-28 FOMC.
The tell to watch. The long end, still. If tomorrow's three-year auction tails and the ten-year presses past 5.35 percent while equities keep setting records, the divergence is widening and the record tape is getting more fragile, not less. Watch the Dow and the Russell 2000 against the mega-cap Nasdaq: the moment higher yields start to bite breadth — the rate-sensitive averages rolling over while the AI complex climbs alone — is the moment this comfortable coexistence starts to end.
Sources
Index, yield, crude and gold closes per Trading Economics and Schwab (Oct 5, 2026); ISM Services PMI (54.9) per ISM/PR Newswire; Schneider–PTC ($22.6B) per Bloomberg and The Boston Globe; C.H. Robinson–RXO ($5.8B) per C.H. Robinson and BNN Bloomberg; Intel/Terafab per Investing.com and Quartz; OPEC+ decision per Trading Economics; Bitcoin per Yahoo Finance; hike-odds per CME FedWatch. The headline Nasdaq figure is the Composite; the Nasdaq-100 closed +0.87% at 31,079.
The Closing Edge is market observation, not investment advice. Closes are as of the bell; values marked with a tilde are near-close estimates, and settlements may adjust.